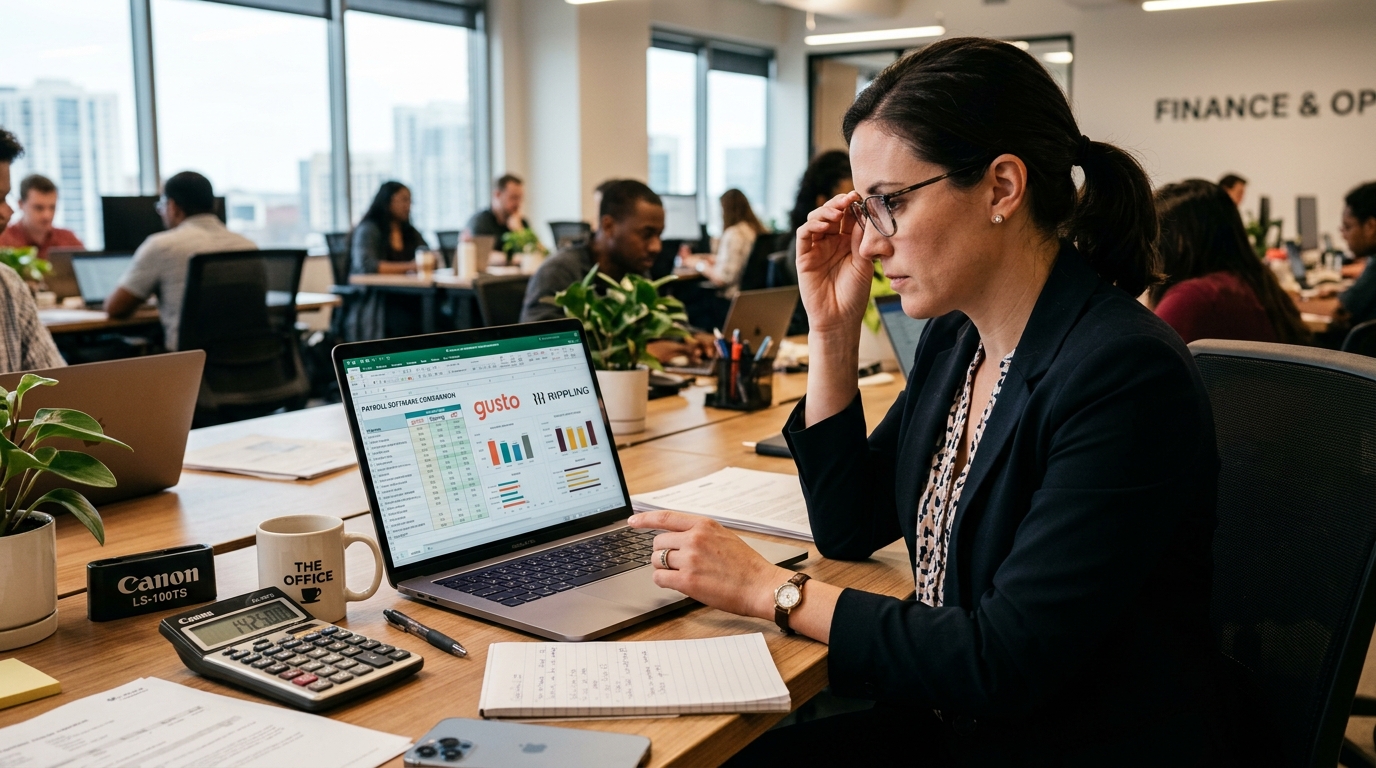
Selecting a payroll and HR platform is one of the most consequential operational decisions for any small-to-midsize business (SMB). While marketing sites proudly display attractive starting base rates, the true annual cost of payroll software is frequently obscured by multi-state tax surcharges, year-end Form W-2/1099 distribution fees, and mandatory implementation charges.
⚡ 2026 Executive Summary & Bottom-Line Verdict
Gusto: Best for 1–25 employees wanting 100% transparent pricing with zero surprise charges. All automated tax filings and W-2s are included in base tiers.
Rippling: Best for fast-growing companies (20–250+ employees) and businesses managing remote or international talent requiring unified HR, IT device management, and payroll.
ADP Run: Best for established SMBs with complex multi-jurisdiction requirements who want custom enterprise contracts, live dedicated payroll specialists, and brand security.
Side-by-Side Cost Breakdown: What You Actually Pay
Below is our standardized cost audit based on an employer running semi-monthly payroll for 15 full-time W-2 employees across 2 US states:
Pricing Metric
Gusto (Simple Plan)
Rippling (Unity + Payroll)
ADP Run (Select Plan)
Base Platform Fee
$40 / month
$35 / month
Quote-based ($60–$100 avg)
Per-Employee-Per-Month (PEPM)
$6 / employee
$8 / employee
$8–$14 / employee
Multi-State Tax Filing Fee
$0 (Included)
$0 (Included)
$15–$35 / extra state / mo
Year-End W-2 / 1099 Generation
$0 (Electronic Included)
$0 (Electronic Included)
$50–$120 base + $4–$6/form
Estimated Total Annual Cost (15 EE)
~$1,560 / year
~$1,860 / year
~$2,800–$3,400 / year
The Hidden Fees Uncovered
1. Year-End Tax Document Delivery Charges
While Gusto delivers digital W-2s and 1099-NEC forms at no added charge within employee portals, legacy bureaus like ADP frequently charge both a “Base Year-End Processing Surcharge” (often $75 to $150) plus an individual fee per mailed or formatted employee tax envelope.
2. Multi-State Nexus Registration Surcharges
Hiring your first remote employee in California, New York, or Texas? Gusto and Rippling automate multi-state withholding calculations natively. However, some traditional vendors bill a recurring fee for registering and submitting quarterly returns in each secondary state.
3. Direct Deposit Speed & Acceleration Penalties
Need next-day or same-day direct deposit? Gusto includes next-day deposit in its Plus tier ($80/mo + $12/ee), whereas ADP may require credit underwriting or reserve impounds before unlocking expedited ACH cycles.
Planning to Switch Payroll Providers This Quarter?
Avoid double tax withholdings and lost year-to-date (YTD) wage files. Download our 7-step payroll migration audit checklist.
Conducting pre-employment background checks is an indispensable component of modern risk management, safeguarding organizations from workplace violence, embezzlement, and negligent hiring liability. However, pre-employment screening is heavily regulated by federal consumer protection statutes and civil rights laws. In 2026, executing candidate screenings without rigid adherence to the Fair Credit Reporting Act (FCRA) and state Fair Chance (“Ban the Box”) laws exposes employers to devastating class action litigation and federal regulatory sanctions.
Executive Key Takeaways for General Counsel, HR Directors & Hiring Managers:
Governing Federal Statutes: Fair Credit Reporting Act (FCRA, 15 U.S.C. § 1681 et seq.), Title VII of the Civil Rights Act of 1964 (EEOC Enforcement Guidance on Arrest and Conviction Records), Driver’s Privacy Protection Act (DPPA, 18 U.S.C. § 2721), and state Fair Chance / “Ban the Box” mandates.
Core Operational Mandate: Enforce the non-negotiable statutory screening protocol: (1) Provide a standalone, document-only FCRA disclosure to the candidate, (2) Secure written candidate authorization, (3) Retain an accredited Consumer Reporting Agency (CRA), (4) Transmit a formal Pre-Adverse Action Notice accompanied by a copy of the report and the FTC Summary of Rights, and (5) Observe a mandatory waiting window (minimum 5 business days) before issuing a Final Adverse Action Notice.
Existential Litigation Exposure: Under 15 U.S.C. § 1681n, “willful” violations of the FCRA trigger statutory damages of $100 to $1,000 per affected candidate without proving actual injury, alongside punitive damages and attorney’s fees. Flawed disclosure forms (such as including liability waivers or extraneous application text) represent the single largest driver of multi-million dollar class action settlements.
Vendor Selection Architecture: Checkr provides superior API automation and ATS integration for scaling tech teams and hourly workforces; GoodHire offers turn-key self-service compliance for small businesses; and Sterling delivers enterprise-scale global verification and accredited security infrastructure.
1. Quick Answer: Best Background Check Services for Employers
The best employer background check services in 2026 balance automated Fair Credit Reporting Act (FCRA) compliance, rapid turnaround times, and direct ATS integration. Checkr leads for technology-forward SMBs and gig workforces, GoodHire delivers straightforward self-service screening for growing companies, and Sterling provides robust global verification for enterprise organizations.
2. The FCRA Statutory Framework: Standalone Disclosures & CRA Rules
The Fair Credit Reporting Act (15 U.S.C. § 1681) governs any consumer report procured for employment purposes. When an employer orders criminal history, driving records (MVR), or credit history from a third-party screening firm, that firm is legally a Consumer Reporting Agency (CRA), and the employer must adhere strictly to statutory authorization protocols.
The Strict Standalone Document Requirement (15 U.S.C. § 1681b(b)(2))
Under 15 U.S.C. § 1681b(b)(2)(A)(i), an employer cannot procure a consumer report unless a clear and conspicuous disclosure has been made in writing to the consumer in a document that consists solely of the disclosure. Federal courts enforce this statutory mandate with zero tolerance:
No Liability Waivers: In the landmark Ninth Circuit ruling Syed v. M-I, LLC (853 F.3d 492), the court held that including a liability waiver or indemnity clause within the FCRA disclosure form constitutes a willful violation of federal law as a matter of law.
No Extraneous Text: Disclosures embedded within employment applications, employee handbooks, or multi-page onboarding packets violate the standalone requirement, instantly creating exposure to class action certification.
Separate Written Consent: The candidate’s written authorization may be bundled on the same standalone page under § 1681b(b)(2)(A)(ii), but modern digital platforms separate disclosure and authorization into distinct digital steps.
The 7-Year Statutory Reporting Cap (15 U.S.C. § 1681c)
Under federal law, CRAs are prohibited from reporting adverse information older than 7 years, including civil suits, civil judgments, and arrest records from date of entry. While federal law permits reporting criminal convictions without a 7-year time limit, several major commercial states (including California, New York, Massachusetts, Washington, and Colorado) enforce strict state statutory 7-year caps on reporting criminal convictions. Modern background check platforms employ automated geo-filtering engines that programmatically redact conviction records older than 7 years based on candidate residence.
When a background report reveals disqualifying criminal history, driving violations, or credentials discrepancies, federal law strictly prohibits the employer from abruptly rescinding the job offer. Employers must execute a formal, two-step Adverse Action workflow mandated by 15 U.S.C. § 1681b(b)(3).
Step 1: The Pre-Adverse Action Notice Package
Before taking any adverse employment decision, the employer must provide the candidate with: (1) Written Pre-Adverse Action Notice stating that disqualifying information was discovered, (2) A complete, unredacted copy of the consumer report procured, and (3) A written copy of the Consumer Financial Protection Bureau’s (CFPB) official notice titled “A Summary of Your Rights Under the Fair Credit Reporting Act.”
The Mandatory Statutory Waiting Period (5 Business Days Minimum)
Federal courts require employers to provide the candidate a “reasonable period of time” to review the report and dispute factual errors or stolen identity records with the CRA before the employer finalizes the hiring rejection. While the FCRA does not specify an exact number of days in statutory text, FTC opinion letters and judicial consensus establish five (5) business days as the mandatory minimum standard. Local laws (e.g., Philadelphia Fair Criminal Records Screening) require 10 business days.
Step 2: The Final Adverse Action Notice
If the candidate does not dispute the record or the CRA confirms the record is accurate after reinvestigation, the employer may issue a formal Final Adverse Action Notice containing: (1) Notice of the adverse decision, (2) Name, address, and toll-free telephone number of the CRA, (3) A statement that the CRA did not make the hiring decision and cannot explain why it was made, and (4) Notice of the candidate’s right to obtain a free copy of the report within 60 days and dispute inaccuracies.
When budgeting for employer screening programs, published SaaS rates only tell half the story. County courts and state DMVs impose mandatory statutory pass-through access surcharges that directly inflate invoice totals. The simulation below models the annual screening budget for a growing business hiring 25 workers across three role profiles.
=== EMPLOYER BACKGROUND SCREENING BUDGET & SURCHARGE MODEL ===
Annual Hiring Target: 25 Hires | Candidate Screening Ratio: 1.2 per hire (30 Total Screens)
Baseline Software Platform: Modern API Screening Engine (Checkr / GoodHire)
The matrix below evaluates the leading background screening platforms across FCRA automation, turnaround times, and integration depth.
Platform
Base Package Pricing
Average Turnaround
Automated Adverse Action Engine
Ban the Box Geo-Filtering
ATS & Payroll Integrations
Mobile Candidate Portal
Best Fit Profile
Checkr
$29.99–$79.99
84% completed <1 hour; 1–2 days avg
1-click automated multi-step workflow
Advanced automated compliance matrix
Gusto, Rippling, Greenhouse, Lever
Top-rated responsive mobile flow
Modern SMBs, tech startups, high-volume gig hiring
GoodHire
$32.99–$89.99
1–3 business days
Guided adverse action wizard
Integrated local law filters
BambooHR, Breezy, Workable
Clean digital signature portal
Small businesses needing straightforward self-service screening
Sterling
Custom contract quote
2–4 business days
Enterprise compliance fulfillment
Dedicated legal rules engine
Workday, SAP SuccessFactors, ADP
Sterling ONE mobile candidate app
Mid-market & enterprise firms with global compliance demands
HireRight
Custom volume pricing
2–5 business days
Comprehensive compliance suite
Standard multi-state rules
Oracle, Taleo, iCIMS
Applicant Center portal
Transportation (DOT), healthcare, and defense contractors
Certn
$25.00–$65.00
Same-day / Real-time
Automated digital notices
Built-in jurisdictional logic
Modern REST API & webhooks
Fast biometric ID verification
International hiring, digital nomads, developer teams
6. Ban the Box Laws, EEOC Disparate Impact & Class Action Defense
Employer liability in background screening extends beyond the FCRA. The Equal Employment Opportunity Commission (EEOC) and state Fair Chance Acts enforce aggressive restrictions on how criminal records are considered.
Statutory Authority
Enforcement Mechanism
Statutory Fine / Damage Exposure
Operational Compliance Guardrail
15 U.S.C. § 1681n
FCRA Willful Non-Compliance Class Action
$100 to $1,000 per candidate + punitive damages & attorney fees
Strict single-page standalone disclosure with zero liability waivers
Title VII (EEOC)
Disparate Impact Disqualification Charges
Back-pay, compensatory damages, mandatory federal monitoring
Mandatory individualized assessment using EEOC Green factors
State Fair Chance Acts
Premature Inquiry Violations (Ban the Box)
$1,000 to $25,000 civil penalty per violation
Conduct background check exclusively after conditional job offer
The EEOC Individualized Assessment (The Green Factors)
Under EEOC Enforcement Guidance, blanket policies stating “any felony conviction automatically disqualifies a candidate” violate Title VII due to demonstrable disparate racial impact. When an adverse criminal record appears, employers must document an individualized assessment based on the three factors established in Green v. Missouri Pacific Railroad (523 F.2d 1290): (1) Nature and gravity of the crime, (2) Time elapsed since the conviction or completion of sentence, and (3) Nature of the specific job sought (e.g., a 6-year-old theft conviction directly relates to a payroll accountant role, but has zero rational bearing on a remote software developer).
Can an employer ask about criminal history on a job application?
In over 37 states and 150 cities with “Ban the Box” and Fair Chance laws, asking about criminal history on initial job applications is illegal. Employers in these jurisdictions may only inquire about criminal background or run a pre-employment screening after an interview has been conducted or a conditional offer of employment has been extended.
How far back can an employer background check go?
Under federal FCRA guidelines, non-conviction arrest records, civil judgments, and bankruptcies are limited to 7 years. While federal law permits reporting criminal convictions indefinitely, many states (including California, Colorado, Kansas, Maryland, Massachusetts, Montana, Nevada, New Hampshire, New Mexico, New York, Texas, and Washington) cap criminal conviction reporting strictly at 7 years for positions under certain salary thresholds.
What is the difference between a Pre-Adverse Action and Final Adverse Action Notice?
A Pre-Adverse Action Notice informs the candidate that potentially disqualifying information was found, includes a copy of their report, and provides at least 5 business days for them to dispute inaccuracies. A Final Adverse Action Notice is sent only after the waiting window expires without a successful dispute, formally rescinding the offer.
Can an employer check an applicant’s credit score?
Employment credit checks do not return a numerical credit score; they provide a credit report showing payment history, bankruptcies, and accounts in collections. Furthermore, 11 states (including California, Colorado, Illinois, Maryland, Nevada, and Washington) strictly restrict employment credit checks unless the role involves executive fiduciary duties or access to over $10,000 in cash.
Can I use social media or Google searches as part of a background check?
Conducting informal Google or social media searches exposes employers to massive discrimination liability because searches inevitably uncover protected demographic characteristics (race, religion, age, sexual orientation, disability, pregnancy). If social screening is performed, it should be conducted by an accredited third-party CRA that filters protected class information and delivers only compliant behavioral reports.
{
“@context”: “https://schema.org”,
“@type”: “FAQPage”,
“mainEntity”: [
{
“@type”: “Question”,
“name”: “Can an employer ask about criminal history on a job application?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “In over 37 states and 150 cities with ‘Ban the Box’ and Fair Chance laws, asking about criminal history on initial job applications is illegal. Employers in these jurisdictions may only inquire after an interview or conditional job offer.”
}
},
{
“@type”: “Question”,
“name”: “How far back can an employer background check go?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Under federal FCRA guidelines, non-conviction records are limited to 7 years. While federal law permits reporting criminal convictions indefinitely, many states cap criminal conviction reporting strictly at 7 years for positions under statutory salary thresholds.”
}
},
{
“@type”: “Question”,
“name”: “What is the difference between a Pre-Adverse Action and Final Adverse Action Notice?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “A Pre-Adverse Action Notice informs the candidate of disqualifying findings, attaches their report, and provides at least 5 business days for review and dispute. A Final Adverse Action Notice is sent only after the waiting window expires, formally rescinding the offer.”
}
},
{
“@type”: “Question”,
“name”: “Can an employer check an applicant’s credit score?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Employment credit checks do not return a numerical credit score; they provide a credit report showing payment history and collections. Furthermore, 11 states strictly restrict credit checks unless the role involves executive fiduciary duties or access to over $10,000 in cash.”
}
},
{
“@type”: “Question”,
“name”: “Can I use social media or Google searches as part of a background check?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Conducting informal Google or social media searches exposes employers to discrimination liability because searches uncover protected demographic characteristics. If social screening is performed, it should be conducted by an accredited CRA that redacts protected class data.”
}
}
]
}
Executive Benchmarks & Related Regulatory Guides
Explore cross-referenced statutory rules, vendor cost evaluations, and operational guides:
Reimbursing employees for business expenses, travel, mileage, and home office stipends seems deceptively simple. Yet behind every reimbursement check or direct deposit lies a minefield of federal tax regulations. In 2026, integrating modern expense management software directly with payroll is essential to maintain an IRS-compliant Accountable Plan, automate receipt capture, and disburse tax-free reimbursements without inflating payroll tax liabilities or triggering IRS reclassification audits.
Executive Key Takeaways for Controllers, CFOs & People Operations:
Governing Federal Statutes: Internal Revenue Code § 62(a)(2)(A) & § 62(c) (Accountable Plan Rules), Treas. Reg. § 1.62-2 (Reimbursements and Other Expense Allowance Arrangements), IRC § 274 (Substantiation Requirements for Business Expenses), and IRS Rev. Proc. 2019-48 (Per Diem and Standard Mileage Safe Harbors).
Core Operational Mandate: Establish an automated Accountable Plan satisfying three statutory tests: (1) Business connection, (2) Factual substantiation within 60 days, and (3) Return of excess advances within 120 days. Compliant reimbursements are 100% tax-free to workers and exempt from employer and employee FICA taxes (15.3% aggregate tax savings).
Existential Non-Compliance Penalty: If expense reporting lacks timely receipt substantiation or policy enforcement, the IRS reclassifies the arrangement as a Non-Accountable Plan under Treas. Reg. § 1.62-2(c)(5). All reimbursements must then be treated as taxable supplemental wages, triggering immediate employer back taxes, failure-to-withhold penalties under IRC § 6656, and retroactive Form W-2c corrections.
Platform Integration Matrix: Ramp delivers best-in-class zero-fee corporate cards and AI receipt reconciliation; Brex excels for venture-backed global teams managing multi-currency spend; Gusto Expenses provides embedded ease for small teams; and Rippling Spend unifies corporate cards, expense reimbursements, and multi-state payroll into a single ledger entry.
1. Quick Answer: Best Expense Management Software Integrated with Payroll
The best expense management software integrated with payroll in 2026 automates IRS Accountable Plan compliance, receipt OCR capture, and tax-free reimbursement disbursements. Ramp leads for zero-fee corporate cards and automated GL sync, Brex excels for venture-backed global teams, and Rippling seamlessly disburses approved employee expenses directly within regular payroll direct deposits.
2. The IRS Accountable Plan Legal Architecture (Treas. Reg. § 1.62-2)
Employee expense reimbursements fall into one of two legal categories under federal tax law: an Accountable Plan or a Non-Accountable Plan. The tax distinction between these two structures is enormous.
The Three Mandatory Statutory Criteria
To qualify as an Accountable Plan under Treasury Regulation § 1.62-2(c)(1), the expense management system must enforce three structural rules without exception:
1. Business Connection (Treas. Reg. § 1.62-2(d)): Expenses must be incurred while performing services as an employee and directly advance the business purpose of the employer (e.g., lodging during commercial travel, business software subscriptions, client meals). Personal expenses cannot be reimbursed under an accountable plan.
2. Substantiation (Treas. Reg. § 1.62-2(e)): Employees must substantiate the amount, time, place, and business purpose of each expense within a reasonable period. Under the IRS fixed-date safe harbor rule, substantiation must occur within 60 days after the expense was paid or incurred. Substantiation requires contemporaneous itemized receipts for any expense of $75 or more (or all lodging expenses regardless of amount under IRC § 274(d)).
3. Return of Excess Amounts (Treas. Reg. § 1.62-2(f)): If an employer provides an expense advance or per diem that exceeds actual substantiated costs, the employee must return the excess funds within a reasonable period (safe harbor standard: within 120 days).
Tax Treatment: Accountable vs. Non-Accountable Plans
When an expense system satisfies all three criteria, reimbursements are completely excluded from employee gross income under IRC § 62(a)(2)(A). They are not reported as wages on Form W-2 (Box 1), and are 100% exempt from federal income tax withholding, employee FICA, employer FICA, and FUTA taxes. Conversely, under a Non-Accountable Plan, every reimbursed dollar is treated as taxable supplemental wages subject to mandatory 22% federal withholding, 7.65% FICA withholding, and 7.65% employer matching taxes.
3. Direct Payroll Integration vs. Standalone ACH Reimbursement
Modern organizations disburse employee reimbursements through two distinct software architectures, each presenting unique operational tradeoffs:
Method 1: Direct On-Paystub Payroll Integration (Gusto, Rippling)
Approved expenses flow automatically into the scheduled payroll run as a dedicated non-taxable earning category. The reimbursement is disbursed directly alongside net wages in the employee’s regular direct deposit. Key Advantages: Unified bank debit, zero separate ACH transaction fees, consolidated pay stubs for employees, and automated general ledger mapping split between Wage Expense and specific Expense accounts.
Method 2: Standalone Out-of-Cycle Direct ACH (Ramp, Brex, Expensify)
Approved expenses trigger an immediate standalone direct deposit to the employee’s personal bank account via ACH within 1 to 2 business days, independent of payroll schedules. Key Advantages: High employee satisfaction due to rapid reimbursement without waiting for bi-weekly payroll cutoff dates. Requires automated general ledger integration to ensure proper double-entry accounting.
4. Mathematical Model: Tax Savings of Accountable Plans vs. Taxable Wages
The calculation model below demonstrates the severe financial penalty of failing to maintain an IRS Accountable Plan for a 12-person firm disbursing $60,000.00 annually in employee travel, mileage, and operational expenses.
=== ACCOUNTABLE PLAN TAX ARBITRAGE SIMULATION ($60,000 ANNUAL SPEND) ===
The matrix below compares the top expense management solutions integrated with payroll systems across features, card programs, and accounting automation.
Platform
Pricing Structure
Corporate Card Program
Direct Payroll Integration
Accountable Plan Safe Harbor Controls
General Ledger API Sync
Mileage Tracking (IRS Rate)
Best Fit Profile
Ramp
Free core platform ($0 SaaS fee)
Unlimited Visa cards with up to 1.5% cashback
Direct ACH next-day or sync to Gusto/Rippling
Automated 60-day receipt cutoff rules
Deep bi-directional sync (QBO, Xero, NetSuite)
Automated IRS rate calculation
Top overall pick for small businesses and scaling teams
Brex
Free essentials tier; $12/user/mo premium
Multi-currency global credit cards
Direct ACH reimbursement across 100+ countries
AI-driven policy compliance engine
Enterprise ERP connectors (NetSuite, Workday)
Built-in mileage calculator
Venture-backed startups and multinational workforces
Rippling Spend
$7/user/mo (Spend management module)
Custom smart corporate cards with card limits
Native paystub integration
Strict receipt blocking & auto-reminders
Unified GL chart of accounts mapping
Native mobile GPS tracking
Companies seeking complete payroll, HR, and spend convergence
Expensify
$5–$9/user/mo
Expensify Visa card with cash back
Syncs to Gusto, QuickBooks, ADP
Custom multi-tier approval rules
QBO, Xero, Sage Intacct
GPS distance and odometer capture
Sales teams with complex multi-stage travel approvals
Gusto Expenses
Included free on Plus ($80 + $12) plan
None (reimbursements only)
Direct paystub inclusion
Basic manager review & receipt upload
Native QBO & Xero payroll journal
Manual mileage calculation entry
Small businesses wanting simple, zero-addon expense workflows
When the IRS audits employer payroll tax returns (Form 941), examining employee reimbursement accounts is standard operating procedure. Auditors evaluate whether non-taxable reimbursements represent disguised wage compensation designed to evade FICA taxes.
IRS Audit Vulnerability
Statutory Code Violation
Enforcement Consequence
Automated Software Mitigation
Missing Itemized Receipts
IRC § 274(d) Substantiation Failure
Disallowance of corporate deduction + conversion to taxable wages
Mobile OCR receipt requirement before reimbursement approval
Late Expense Submissions (>60 Days)
Treas. Reg. § 1.62-2(e)(2)
Plan reclassified as Non-Accountable; 15.3% back FICA assessed
Automatic policy rule blocking claims older than 60 calendar days
Round-Number Stipends without Receipts
Treas. Reg. § 1.62-2(c)(5)
Full retroactive W-2 wage reclassification + IRC § 6656 penalties
Replacing unverified cash stipends with receipt-backed software programs
Digital Receipt Retention Standards (Rev. Proc. 98-25)
Under IRS Revenue Procedure 98-25 and Rev. Proc. 97-22, digital images of paper receipts satisfy statutory recordkeeping requirements provided the electronic storage system maintains legibility, ensures indexing for rapid retrieval, and preserves audit log integrity. Utilizing a cloud expense platform that archives high-resolution receipt images permanently tied to general ledger transaction records provides complete audit protection during federal and state tax examinations.
Are employee expense reimbursements subject to payroll taxes?
No, provided the reimbursements are made under an IRS-compliant Accountable Plan that requires business connection, timely receipt substantiation within 60 days, and return of excess funds within 120 days. Under an Accountable Plan, reimbursements are 100% tax-free to employees and exempt from employer FICA and FUTA taxes.
Can an employer pay a flat monthly cell phone or internet stipend tax-free?
Under IRS Notice 2011-72, cell phone reimbursements provided primarily for non-compensatory business reasons can be treated as a tax-free working condition fringe benefit without detailed call logging. However, general remote work stipends or internet allowances that do not require employees to substantiate actual business costs are considered Non-Accountable and must be treated as taxable wages subject to payroll tax withholding.
How does mileage reimbursement work under IRS guidelines?
Employers can reimburse employees tax-free using the IRS Standard Mileage Rate (or actual vehicle operating costs). To qualify under an Accountable Plan, employees must substantiate their business mileage with a log documenting: (1) Date of travel, (2) Total miles driven, (3) Destination, and (4) Business purpose. Reimbursing above the federal rate makes the excess portion taxable income.
Is it better to reimburse expenses through payroll or via corporate cards?
Corporate card platforms (like Ramp or Brex) are superior for recurring business operational expenses because the company pays the vendor directly, eliminating employee out-of-pocket cash burdens and offering 1.5% cashback. Payroll reimbursements are ideal for personal vehicle mileage, per diems, and incidental out-of-pocket expenses incurred by staff who do not hold corporate cards.
Do employees have to submit receipts for small expenses under $75?
Under IRC § 274(d) and Treasury Regulations, receipts are statutorily required for all lodging expenses (regardless of amount) and any other business expense of $75 or more. However, best corporate governance practices—and modern software platforms—enforce receipt capture for all transactions regardless of dollar threshold to eliminate audit dispute ambiguity.
{
“@context”: “https://schema.org”,
“@type”: “FAQPage”,
“mainEntity”: [
{
“@type”: “Question”,
“name”: “Are employee expense reimbursements subject to payroll taxes?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “No, provided the reimbursements are made under an IRS-compliant Accountable Plan requiring business connection, timely receipt substantiation within 60 days, and return of excess funds within 120 days.”
}
},
{
“@type”: “Question”,
“name”: “Can an employer pay a flat monthly cell phone or internet stipend tax-free?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Under IRS Notice 2011-72, cell phone reimbursements provided primarily for business purposes can be treated as tax-free working condition fringe benefits. However, general un-substantiated remote work stipends must be treated as taxable wages.”
}
},
{
“@type”: “Question”,
“name”: “How does mileage reimbursement work under IRS guidelines?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Employers can reimburse employees tax-free using the IRS Standard Mileage Rate. Employees must substantiate their mileage with a log documenting date, miles driven, destination, and business purpose.”
}
},
{
“@type”: “Question”,
“name”: “Is it better to reimburse expenses through payroll or via corporate cards?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Corporate card platforms (like Ramp or Brex) are superior for recurring business expenses because the company pays directly and earns cashback. Payroll reimbursements are ideal for mileage and incidental out-of-pocket expenses.”
}
},
{
“@type”: “Question”,
“name”: “Do employees have to submit receipts for small expenses under $75?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Under IRC § 274(d), receipts are statutorily required for lodging and any business expense of $75 or more. However, best corporate governance practices enforce receipt capture for all transactions.”
}
}
]
}
Executive Benchmarks & Related Regulatory Guides
Explore cross-referenced statutory rules, vendor cost evaluations, and operational guides:
Managing Paid Time Off (PTO), sick leave, and statutory leave policies has transformed into one of the most perilous legal battlegrounds for growing small businesses. In 2026, with remote employees distributed across multiple states and municipal jurisdictions, managing leave on manual spreadsheets is an invitation to costly wage theft lawsuits. Implementing modern PTO tracking software integrated directly with payroll ensures continuous compliance with state mandatory paid sick leave laws, prevents illegal leave forfeitures, and automates precision final wage payouts.
Executive Key Takeaways for Founders, HR Leaders & Payroll Officers:
Governing Federal & State Statutes: Family and Medical Leave Act (FMLA, 29 U.S.C. § 2601), Fair Labor Standards Act (FLSA, 29 U.S.C. § 201), California Labor Code § 227.3 (Vested Vacation Pay Protections), Colorado Wage Claim Act (C.R.S. § 8-4-101), Illinois Paid Leave for All Workers Act (820 ILCS 192/), and mandatory paid sick leave statutes in 18+ states.
Core Operational Mandate: Automate complex multi-tiered accrual models (e.g., tenure-based accrual rates, per-hour-worked accruals, annual frontloading), enforce statutory sick leave minimums based on employee physical work location, and maintain real-time bi-directional balance synchronization between time-tracking tools and payroll ledgers.
Existential Legal Liabilities: In states such as California, Colorado, and Montana, accrued vacation time is legally classified as deferred wages. Maintaining “use-it-or-lose-it” forfeiture policies is illegal. Failing to cash out accrued PTO upon separation triggers devastating waiting time penalties under statutes like Cal. Lab. Code § 203 (up to 30 days of full daily wages per affected employee) plus mandatory attorney fees.
Platform Selection Architecture: Gusto provides native, single-click PTO tracking with automated payroll wage deduction; BambooHR excels at intuitive visual company calendars and multi-tier approval chains; and Rippling delivers automated 50-state statutory leave policy compliance that dynamically adapts as remote workers relocate.
1. Quick Answer: Best PTO & Leave Tracking Software for SMBs
The best PTO and leave tracking software for small businesses in 2026 automates multi-state paid sick leave compliance, complex accrual formulas, and final separation wage payouts. Gusto provides seamless native payroll synchronization, BambooHR delivers intuitive calendar visibility and approval workflows, while Rippling automatically configures statutory leave policies based on remote employee physical locations.
2. Statutory Landscape: The “PTO As Vested Wages” Legal Doctrine
While the federal Fair Labor Standards Act (FLSA) does not mandate paid vacation or sick leave, state and municipal employment statutes establish aggressive, legally binding frameworks governing how leave is accrued, utilized, and paid out.
The Suastez Doctrine: Vacation as Vested Wages
Under California Labor Code § 227.3 and the California Supreme Court’s landmark ruling in Suastez v. Plastic Dress-Up Co. (31 Cal.3d 774), paid vacation and combined PTO are defined as deferred compensation for labor performed. As an employee works, their right to vacation pay vests day-by-day. Crucially, this statutory vesting triggers two inviolable legal rules:
1. Strict Prohibition of “Use-It-or-Lose-It” Policies: Employers cannot enforce policies that forfeit unused accrued vacation at year-end. Such forfeitures constitute illegal wage confiscation. (Employers may, however, establish reasonable accrual caps to halt further accruals once a ceiling is met).
2. Mandatory Separation Cash-Out: Upon termination or resignation, all vested, unused vacation time must be cashed out at the employee’s final wage rate on the final paycheck. Disclaiming PTO payout in an employee handbook is void against public policy in California, Colorado, Montana, and Nebraska.
Mandatory Paid Sick Leave Laws Across 18+ States
Unlike discretionary vacation, statutory paid sick leave is mandated by law in states including California (5 days / 40 hours minimum), New York (up to 56 hours based on employer size), Washington, Colorado, New Jersey, and Illinois. These statutes prescribe precise accrual minimums (typically 1 hour of paid sick leave per 30 or 40 hours worked) and establish strict retaliation protections under state labor codes. Modern PTO software must dynamically apply statutory sick leave rules to prevent administrative non-compliance.
3. Accrual Architecture: Hourly vs. Lump-Sum & Use-It-or-Lose-It Pitfalls
Organizations structure employee leave through three technical accrual architectures. Matching the correct structure to employee classifications is vital to avoid compliance errors:
Model 1: Hourly Accrual (Standard for Non-Exempt Staff)
Employees earn a precise fraction of a leave hour for every hour worked (e.g., 0.0577 hours per regular hour worked = 120 hours annually over 2,080 hours). Modern software ties directly to digital timecard punches, calculating exact accrual balances on each pay run while automatically excluding overtime hours from accrual bases where appropriate.
Model 2: Pay-Period Allotment (Standard for Salaried Exempt Staff)
A fixed leave credit is granted at the close of every pay cycle (e.g., 5.0 hours semi-monthly or 4.615 hours bi-weekly). This model provides predictable leave progression that synchronizes cleanly with corporate accounting accrual schedules.
Model 3: Frontloaded Lump-Sum / “Unlimited PTO”
The entire annual allotment (or open-ended time off) is granted on January 1 or the employee’s service anniversary. Critical Warning: While unlimited PTO theoretically eliminates balance tracking and year-end separation cash-outs, recent California appellate rulings (McPherson v. EF Intercultural, Inc.) hold that “unlimited” policies that in practice discourage time off or operate with informal caps still trigger mandatory cash-out liabilities upon termination.
4. Mathematical Model: Hourly Accrual Formulas & Final Separation Payouts
The mathematical model below demonstrates the operational accrual formulas and the catastrophic financial penalty of miscalculating final PTO payouts upon employee departure.
The matrix below compares the top leave management software solutions across accrual rules, multi-state sick leave compliance, and payroll synchronization.
Platform
Pricing Structure
Accrual Formula Flexibility
Multi-State Statutory Sick Engine
Native Payroll Integration
Calendar Sync (Google/Outlook/Slack)
Automated Final Cashout Calculation
Best Fit Profile
Gusto (Plus / Prem)
Included on Plus ($80 + $12/user)
Hourly, per-pay-period, and annual grant
Automated statutory state templates
Direct embedded sync to paystub
Google Calendar, Outlook, Slack
Automatic calculation on termination run
General small businesses wanting unified zero-friction payroll & PTO
BambooHR
Included in Advantage HRIS tier
Highly granular tenure-based tiers
Custom statutory policy builder
Syncs to BambooHR Payroll, Trax, ADP
Industry-leading visual company calendar
Manual review or automated payroll export
Growing organizations prioritizing manager approvals and calendar visibility
Rippling Time Off
$4–$6/user/mo module
Unlimited custom formula logic
Automated 50-state compliance engine
Native real-time ledger auto-deduct
Real-time Slack approvals & status sync
State-specific mandatory cashout auto-post
Distributed tech teams and complex multi-state workforces
Deputy
$4.50/user/mo
Shift-based and clocked-hours accrual
Predictive scheduling compliance
Connects to Gusto, ADP, Square
Mobile shift roster calendar
Exportable wage register
Restaurants, retail, healthcare, and hourly shift environments
OnPay Time Off
Included standard in $40 + $6 flat rate
Standard accruals and custom balances
Pre-configured state sick guidelines
Direct payroll paystub sync
Exportable calendar feeds
Integrated final pay run calculation
Cost-conscious small teams seeking zero add-on fees
Monthly statutory damages of 5% of unpaid balance under Illinois Wage Payment Act
Establishing Compliant Accrual Caps vs. Illegal Forfeitures
While employers in California and Colorado cannot erase or forfeit accrued vacation time, state labor commissioners affirm that employers have the legal right to enforce an Accrual Cap (typically 1.5x to 2x the annual accrual limit). Once an employee’s balance reaches the cap, further accruals cease until the employee takes time off and drops below the ceiling. Modern software platforms enforce these caps automatically, preventing runaway corporate balance sheet liabilities without violating anti-forfeiture statutes.
Can an employer enforce a “use-it-or-lose-it” PTO policy?
It depends strictly on state law. In California, Colorado, Montana, and Nebraska, “use-it-or-lose-it” policies that forfeit earned vacation time are illegal, as PTO is classified as vested wages. However, employers may establish reasonable accrual caps (e.g., capping maximum balance at 1.5 times annual accrual). In other states, use-it-or-lose-it is permissible only if explicitly stated in a signed, written employee handbook.
Does an employer have to pay out unused PTO when an employee quits?
In states with mandatory vacation payout statutes (such as California, Colorado, Illinois, Indiana, Louisiana, Maryland, Massachusetts, Montana, Nebraska, and North Dakota), employers must pay out all earned, unused vacation on the employee’s final paycheck. In other states, payouts are dictated by company written policy.
What is the difference between PTO and Statutory Paid Sick Leave?
PTO is a combined discretionary bucket encompassing vacation, personal time, and illness. Statutory Paid Sick Leave is mandated by state or municipal law for specific health-related events, medical care, or family illness. When employers combine sick leave and vacation into a single PTO policy, state laws (like in California) often require the entire combined balance to be treated under strict vacation wage protection rules.
How does PTO tracking software sync with payroll?
Modern software links leave requests directly to the payroll engine. When an employee takes 8 hours of PTO, the software automatically decrements their leave bank, populates 8 hours of paid leave earnings onto their digital paystub, and deducts the appropriate wage expense on the general ledger without manual administrative entry.
Does Unlimited PTO really protect employers from separation payouts?
Under proper legal implementation, Unlimited PTO eliminates accrued balance tracking, so there is no formal accrued balance to cash out upon separation. However, if the company implicitly enforces accrual tracking, restricts time off unfairly, or treats the policy as informal, courts (especially in California) may find the unlimited policy to be a sham and calculate back-pay wage liabilities.
{
“@context”: “https://schema.org”,
“@type”: “FAQPage”,
“mainEntity”: [
{
“@type”: “Question”,
“name”: “Can an employer enforce a ‘use-it-or-lose-it’ PTO policy?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “It depends strictly on state law. In California, Colorado, Montana, and Nebraska, ‘use-it-or-lose-it’ policies that forfeit earned vacation time are illegal, as PTO is classified as vested wages. However, employers may establish reasonable accrual caps.”
}
},
{
“@type”: “Question”,
“name”: “Does an employer have to pay out unused PTO when an employee quits?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “In states with mandatory vacation payout statutes (such as California, Colorado, Illinois, and Massachusetts), employers must pay out all earned, unused vacation on the final paycheck. In other states, payouts are dictated by written company policy.”
}
},
{
“@type”: “Question”,
“name”: “What is the difference between PTO and Statutory Paid Sick Leave?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “PTO is a combined discretionary bucket encompassing vacation and personal time. Statutory Paid Sick Leave is mandated by state law for health-related events. When combined into a single PTO policy, state laws often require the entire balance to be treated under strict vacation wage protection rules.”
}
},
{
“@type”: “Question”,
“name”: “How does PTO tracking software sync with payroll?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Modern software links leave requests directly to the payroll engine. When an employee takes leave, the software automatically decrements their leave bank, populates paid leave earnings onto their paystub, and updates the general ledger.”
}
},
{
“@type”: “Question”,
“name”: “Does Unlimited PTO really protect employers from separation payouts?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Under proper legal implementation, Unlimited PTO eliminates accrued balance tracking, leaving no balance to cash out. However, if the policy operates with informal caps or discourages time off, courts may deem it a sham and assess wage liabilities.”
}
}
]
}
Executive Benchmarks & Related Regulatory Guides
Explore cross-referenced statutory rules, vendor cost evaluations, and operational guides:
For growing small businesses and mid-market organizations, performance management has evolved from an obsolete, dreaded annual review into a continuous, data-driven operational discipline. In 2026, implementing modern performance management software is not simply about boosting employee morale—it is the foundational mechanism for aligning workforce execution with business objectives, calibrating equitable compensation, and erecting an unassailable legal defense against wrongful termination and employment discrimination claims.
Executive Key Takeaways for CEOs, HR Leaders & People Operations:
Governing Federal Employment Statutes: Title VII of the Civil Rights Act of 1964 (42 U.S.C. § 2000e et seq.), Age Discrimination in Employment Act (ADEA, 29 U.S.C. § 621), Americans with Disabilities Act (ADA, 42 U.S.C. § 12101), and the Equal Employment Opportunity Commission (EEOC) Uniform Guidelines on Employee Selection Procedures (29 CFR Part 1607).
Core Operational Framework: Replace subjective once-a-year appraisals with continuous performance systems integrating structured weekly 1:1 check-ins, quantitative Objectives and Key Results (OKRs), peer 360-degree reviews, and objective merit-based compensation calibrations directly linked to payroll.
Legal Exposure & Wrongful Termination Defense: Under federal disparate treatment doctrine (McDonnell Douglas Corp. v. Green), contemporaneous, objective, and timestamped performance reviews provide the critical evidence required to defeat employee wrongful discharge, retaliation, and wage discrimination claims. Subjective supervisor notes consistently fail EEOC scrutiny.
Platform Selection Architecture: Lattice leads venture-backed scaling organizations requiring sophisticated compensation benchmarking; BambooHR provides an all-in-one HRIS with embedded performance scoring; 15Five excels at structured manager enablement and weekly feedback loops; and Rippling seamlessly connects performance ratings directly into automated payroll compensation adjustments.
1. Quick Answer: Best Performance Management Software for SMBs
The best performance management software for growing small businesses in 2026 balances continuous 1:1 feedback, quantitative OKR tracking, and EEOC-defensible evaluation documentation. Lattice excels for venture-backed tech teams, BambooHR delivers seamless HRIS integration, 15Five drives manager coaching cadence, and Rippling automatically synchronizes performance ratings with merit increases in payroll.
2. The Legal Architecture: EEOC Guidelines & Title VII Documentation
Performance evaluations are not merely human resources artifacts; under federal employment jurisprudence, they are formal employment tests. Under the EEOC Uniform Guidelines on Employee Selection Procedures (29 CFR Part 1607.2), any procedure used to make employment decisions—including promotion, demotion, salary adjustment, or termination—falls under strict regulatory scrutiny.
The Burden of Proof in Employment Litigation
In federal employment litigation governed by Title VII, the ADEA, or the ADA, courts utilize the tripartite burden-shifting framework established in McDonnell Douglas Corp. v. Green (411 U.S. 792):
Prima Facie Claim: The plaintiff employee establishes they belong to a protected class, performed satisfactorily, suffered an adverse employment action (e.g., termination or passed-over promotion), and were replaced by someone outside the protected class.
Legitimate Non-Discriminatory Reason: The burden shifts to the employer to articulate a legitimate, non-discriminatory business reason for the adverse action. This reason must be substantiated by contemporaneous, factual documentation.
Pretext Analysis: The employee attempts to prove the employer’s stated reason is a pretext for discrimination. If a supervisor claimed an employee was fired for poor performance, but performance reviews show “Meets Expectations” ratings without written disciplinary notes, courts routinely find pretext, resulting in massive employer liability.
Eliminating Evaluation Biases via Structured Software
Modern performance platforms systematically eliminate cognitive biases that expose companies to legal jeopardy:
Recency Bias: Where managers evaluate employees solely based on the last 30 days of work rather than the entire annual cycle. Software solves this by archiving weekly 1:1 notes and monthly goal progression.
Central Tendency Bias: Where managers rate everyone in the middle to avoid conflict, stripping high performers of merit pay and depriving low performers of documented notice.
Halo / Horns Effect: Where a single trait unduly influences the entire evaluation rubric. Modern platforms require competency-based behavioral rubrics with mandatory text justifications for outlier ratings.
High-performing organizations structure their talent operations around a four-pillar operational cadence that replaces static annual appraisals with continuous operational alignment.
Pillar 1: Quarterly OKRs & Cascading Key Results
Objectives and Key Results (OKRs) ensure qualitative aspirations are tethered to quantitative metrics. Company objectives cascade into departmental key results, which branch into individual quarterly goals. Software platforms track live percentages of completion, providing empirical data when review cycles commence.
Pillar 2: Structured Bi-Directional 1:1 Check-ins
Weekly or bi-weekly 1:1 meetings are guided by structured agendas covering blockers, priorities, and psychological safety. Both manager and employee collaborate in real-time, creating a persistent, immutable digital paper trail of feedback, coaching, and agreed-upon action items.
Pillar 3: Multi-Rater 360-Degree Feedback
Evaluating individuals solely through a direct manager’s lens creates organizational blind spots. 360-degree reviews capture upward feedback from direct reports, lateral feedback from cross-functional peers, and self-evaluations, synthesizing a comprehensive, holistic assessment.
Pillar 4: Performance Improvement Plans (PIPs) with Milestone Gates
When performance falls below standard, the software initiates a formal PIP workflow with 30, 60, and 90-day milestone checkpoints, explicit performance criteria, and required employee acknowledgments, protecting the organization from claims of abrupt termination.
To eliminate arbitrary favoritism and maintain strict fiscal discipline, modern enterprises utilize an algorithmic Merit Increase Matrix. The model below demonstrates how a 30-employee company with a $2,400,000 annual wage budget allocates a 3.5% merit budget ($84,000 pool) balancing Performance Ratings against market Compa-Ratios.
=== ALGORITHMIC MERIT INCREASE MATRIX & COMPENSATION MODEL ===
The matrix below compares the top performance management solutions across features, compensation calibration capabilities, and payroll integration depth.
Platform
Pricing Structure
Goal & OKR Tracking
360 Feedback & 1:1 Cadence
Compensation Calibration Module
Payroll / HRIS Integration
Audit & Legal Export
Best Fit Profile
Lattice
$11/user/mo (Performance + OKRs)
Comprehensive cascading OKRs
Full 360, peer praise, 1:1s
Advanced (Lattice Compensation add-on)
Gusto, Rippling, ADP, Workday
Timestamped PDF/CSV audit trail
High-growth startups, remote technology companies
BambooHR
Adv. HRIS plan + Performance add-on
Simplified goal management
Semi-annual streamlined assessments
Basic salary history tracking
Native embedded HRIS & Payroll
Unified employee folder records
Traditional SMBs seeking simple, low-friction reviews
15Five
$4–$14/user/mo
Robust OKR management
Industry-leading weekly check-in flow
Basic rating-to-salary linkage
Gusto, BambooHR, Namely
Continuous historical logs
Companies focused on frontline manager enablement
Culture Amp
Custom enterprise pricing
Goal alignment tools
Deep behavioral science 360s
Analytics-driven compensation bands
All major HRIS connectors
Enterprise compliance compliance
Mid-market & enterprise data-driven cultures
Rippling Performance
$8/user/mo (Performance module)
Dynamic team & individual OKRs
Automated recurring reviews & 1:1s
Direct payroll auto-update
Native Rippling Unity ecosystem
Complete immutable system logs
Teams wanting zero manual data entry between reviews & pay
In wrongful termination and employment discrimination claims, the outcome of litigation is almost never decided by what occurred on the day of termination—it is decided by the documentation created during the six to twelve months leading up to the event.
Legal Exposure Vector
Average Employer Exposure
Flawed Operational Practice
Software Compliance Solution
Wrongful Termination Claims
$75,000–$250,000 in defense & settlement
Falsely positive appraisals (“inflated reviews”) right before firing
Mandatory calibration sessions and objective competency rubrics
Title VII Retaliation Claims
Statutory damages + attorney fees
Sudden poor reviews immediately following an employee complaint
Unexplained wage disparities between protected and non-protected groups
Algorithmic merit matrix with compa-ratio tracking documenting non-discriminatory reasons
The Anatomy of an Legally Unassailable PIP
To defend against wrongful termination charges, every Performance Improvement Plan managed through your performance platform must satisfy five statutory criteria: (1) Specificity: Detailed citations of deficient deliverables rather than vague behavioral complaints; (2) Measurability: Objective milestones with verifiable outputs; (3) Support: Explicit employer resources and weekly coaching check-ins; (4) Timeline: Realistic 30 to 60-day durations; and (5) Acknowledgment: Timestamped digital signatures acknowledging that failure to meet standards results in termination of employment.
7. Frequently Asked Questions (FAQ)
How often should a growing small business conduct performance reviews?
The industry standard for fast-growing small businesses in 2026 is a hybrid continuous model: lightweight bi-weekly or monthly 1:1 coaching check-ins combined with quarterly OKR goal assessments and semi-annual or annual formal compensation review cycles. Abandoning annual-only reviews eliminates recency bias and keeps employees continuously aligned.
What is the difference between an OKR and a KPI?
A KPI (Key Performance Indicator) is a metric that monitors ongoing business health and operational baseline performance (e.g., maintaining 99.9% uptime or average customer ticket response time under 2 hours). An OKR (Objective and Key Result) is an ambitious, time-bound strategic initiative designed to drive growth or change (e.g., Objective: Expand into European enterprise market; Key Result: Acquire 15 certified GDPR enterprise pilots by Q3).
How do performance management tools integrate with payroll software?
Integrated platforms like Rippling natively sync performance scores and approved merit increases directly into payroll compensation tables, eliminating manual spreadsheet imports. Standalone performance platforms like Lattice connect via direct API to Gusto, ADP, or BambooHR, automatically exporting calibrated compensation increases, bonuses, and title changes into the payroll ledger upon executive approval.
Can an employee sue an employer over a negative performance review?
Generally, a negative performance appraisal alone is not considered an “adverse employment action” under federal law unless it directly results in tangible harm, such as a demotion, denial of promotion, reduction in pay, or termination. However, if a negative review is weaponized as retaliation after an employee reports harassment or wage theft, it serves as key evidence in a Title VII or FLSA retaliation lawsuit.
What is a 9-Box Grid and is it still relevant for small teams?
A 9-Box Grid is a talent management matrix that plots employees on an X-axis (Current Performance) and Y-axis (Future Potential). While valuable for succession planning in organizations with over 50 employees to identify future leaders and flight risks, smaller teams under 25 people typically benefit more from direct OKR tracking and continuous 1:1 feedback loops rather than abstract potential scoring.
{
“@context”: “https://schema.org”,
“@type”: “FAQPage”,
“mainEntity”: [
{
“@type”: “Question”,
“name”: “How often should a growing small business conduct performance reviews?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “The industry standard for fast-growing small businesses in 2026 is a hybrid continuous model: lightweight bi-weekly or monthly 1:1 coaching check-ins combined with quarterly OKR goal assessments and semi-annual or annual formal compensation review cycles.”
}
},
{
“@type”: “Question”,
“name”: “What is the difference between an OKR and a KPI?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “A KPI (Key Performance Indicator) is a metric that monitors ongoing business health and operational baseline performance. An OKR (Objective and Key Result) is an ambitious, time-bound strategic initiative designed to drive growth or change.”
}
},
{
“@type”: “Question”,
“name”: “How do performance management tools integrate with payroll software?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Integrated platforms like Rippling natively sync performance scores and approved merit increases directly into payroll compensation tables. Standalone performance platforms like Lattice connect via direct API to Gusto, ADP, or BambooHR, automatically exporting calibrated compensation increases.”
}
},
{
“@type”: “Question”,
“name”: “Can an employee sue an employer over a negative performance review?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Generally, a negative performance appraisal alone is not considered an adverse employment action under federal law unless it directly results in tangible harm, such as a demotion, denial of promotion, reduction in pay, or termination.”
}
},
{
“@type”: “Question”,
“name”: “What is a 9-Box Grid and is it still relevant for small teams?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “A 9-Box Grid is a talent management matrix that plots employees on an X-axis (Current Performance) and Y-axis (Future Potential). While valuable for succession planning in organizations over 50 employees, smaller teams benefit more from direct OKR tracking and continuous 1:1 feedback loops.”
}
}
]
}
Executive Benchmarks & Related Regulatory Guides
Explore cross-referenced statutory rules, vendor cost evaluations, and operational guides:
Workers’ compensation insurance is a non-negotiable statutory requirement for operating a business in the United States. In 49 states, employing even a single non-owner W-2 worker mandates active coverage. However, the traditional method of procuring workers’ comp—involving massive upfront cash deposits, arbitrary annual payroll estimates, and punishing year-end audit adjustments—wreaks havoc on small business cash flow. In 2026, integrating Pay-As-You-Go workers’ compensation directly with your payroll software eliminates audit surprises, protects operating capital, and guarantees continuous state statutory compliance.
Executive Key Takeaways for Managing Partners, CFOs & Operations Directors:
Governing Statutory Mandate: State Workers’ Compensation Acts across 49 states (exclusive remedy doctrine), National Council on Compensation Insurance (NCCI) classification systems, state Department of Insurance rate regulations, and statutory employer liability codes.
Core Operational Paradigm: Replace legacy “estimated annual policies” with real-time “Pay-As-You-Go” integration. Instead of paying a 15% to 25% upfront down payment based on speculative wage forecasts, the payroll engine calculates exact premium dues on each actual pay run based on employee NCCI classification codes and transmits payments automatically to the insurance carrier.
Audit Shock & Penalty Exposure: Under traditional policies, expanding headcount or paying overtime during the year triggers devastating year-end audit invoices (often $5,000 to $25,000+) due within 30 days. Operating without active coverage triggers immediate state Stop-Work Orders, civil penalties up to $1,000 per day, and unlimited personal tort liability for workplace injuries.
Platform Carrier Ecosystem: Modern cloud payroll engines (Gusto, OnPay, QuickBooks, Rippling) partner directly with national carriers (NEXT Insurance, The Hartford, Travelers, AmTrust, Berkshire Hathaway GUARD) to provide zero-down-payment pay-as-you-go coverage with automated year-end audit synchronization.
1. Quick Answer: Pay-As-You-Go vs. Traditional Workers’ Comp
Pay-As-You-Go workers’ compensation links insurance premiums directly to real-time payroll runs in 2026, eliminating large upfront cash deposits (15%–25%) and devastating year-end audit bills. Premiums are calculated automatically on actual gross wages by NCCI risk classification and debited each pay period, preserving working capital and ensuring continuous statutory coverage.
2. The Statutory Framework: Mandatory Coverage, NCCI Codes & EMR
Workers’ compensation is the oldest social insurance system in the United States, established as a “grand bargain” between employers and employees: in exchange for guaranteed no-fault medical coverage and partial wage replacement for injured workers, employees surrender their common-law right to sue the employer for workplace negligence (the exclusive remedy doctrine).
State Coverage Mandates & Thresholds
Workers’ compensation is strictly regulated at the state level. While Texas remains the only state permitting private employers to “opt out” as non-subscribers under Texas Labor Code § 406.002 (at the cost of forfeiting all common-law defenses in injury lawsuits), every other state mandates active coverage:
1-Employee Threshold States: California, New York, Florida, Illinois, Pennsylvania, and over 35 other states mandate active coverage the instant an entity hires its first non-owner W-2 employee.
Monopolistic State Funds: Four states—Ohio, Washington, North Dakota, and Wyoming—do not permit private insurance carriers. Employers must secure coverage directly through the state-operated workers’ compensation fund.
The NCCI Classification Code Architecture & Formula
Workers’ compensation premiums are not assessed uniformly across total company wages. They are determined by the specific hazard risk of the work performed, categorized under 4-digit codes established by the National Council on Compensation Insurance (NCCI):
Code 8810 (Clerical Office Employees): Low hazard risk; typical base rate is $0.15 to $0.40 per $100 of gross payroll.
Code 8742 (Outside Sales / Messengers): Moderate risk; typical base rate is $0.45 to $0.90 per $100 of gross payroll.
Code 5403 (Carpentry / Construction): High hazard risk; typical base rate ranges from $8.00 to $18.00+ per $100 of gross payroll.
The standard statutory premium calculation formula is:
Base Premium = (Gross Payroll / 100) x NCCI Class Rate x Experience Modification Rate (EMR)
3. Operational Mechanics: How Pay-As-You-Go Eliminates Down Payments
Comparing the operational lifecycles of traditional audited policies versus modern pay-as-you-go architectures reveals why the industry is rapidly transitioning to automated integration:
The Traditional Audited Policy Flaw
Upfront Cash Drain: Employer estimates annual payroll at policy inception. Carrier demands a mandatory 15% to 25% non-refundable deposit.
Fixed Installments: The remaining balance is billed in 9 or 10 equal monthly installments based on the original estimate, regardless of whether seasonal staffing drops or payroll shrinks.
The Year-End Audit Trap: After 12 months, a forensic auditor examines actual payroll registers. If actual payroll exceeded estimates due to growth or overtime, the employer receives an immediate, non-negotiable invoice for the unpaid premium balance due within 30 days.
The Modern Pay-As-You-Go Solution
Zero Upfront Down Payment ($0 Deposit): Policy is bound with zero initial deposit. Capital remains in company operating reserves.
Real-Time Wage Ingestion: On every pay run, the payroll software securely transmits exact wages categorized by employee NCCI code via API to the insurance carrier.
Exact Micro-Debits: Premium is debited automatically from the commercial bank account per pay cycle down to the penny. If payroll declines during slow months, premium expense instantly drops.
Zero Audit Surprise: Because actual wages were reported and paid in real time, the year-end audit is a simple 5-minute digital sign-off with $0 balance due.
The simulation below models the cash flow impact for a growing commercial contractor with 14 employees. The company projected $1,200,000 in baseline annual payroll across clerical (Code 8810) and skilled trade (Code 5403) roles, but experienced strong growth, closing the year with $1,500,000 in actual gross payroll.
The matrix below compares the top payroll software platforms across workers’ compensation insurance partnerships, down payment policies, and audit automation.
Payroll Platform
Insurance Broker / Partner
Upfront Down Payment
Supported National Carriers
Multi-State Code Splitting
Bring-Your-Own-Broker
Year-End Audit Automation
Best Fit Profile
Gusto
Gusto Embedded Brokerage (NEXT, AP Intego)
$0 deposit standard
The Hartford, Travelers, NEXT, AmTrust
Automated employee-level NCCI mapping
Supported via select API partners
100% digital audit report export
General small businesses wanting turnkey quote-to-bind workflow
OnPay
In-house licensed insurance agency
$0 deposit standard
GUARD, The Hartford, Travelers, Pie
Granular class code splitting per job
Yes (integrates existing policies)
Free audit report assistance
Agricultural, trade contractors, and small teams wanting broker choice
QuickBooks Payroll
QuickBooks Insurance (powered by NEXT)
$0 deposit standard
NEXT Insurance, Employers, Markel
Standard QBO payroll class mapping
Limited external connectivity
Automated QBO payroll summary
Firms deeply integrated in QuickBooks Online ecosystem
ADP RUN
ADPIA (Automatic Data Processing Ins. Agency)
$0 deposit on approved carriers
Extensive national network (50+ carriers)
Enterprise-grade multi-location splitting
Yes (requires broker interface fee)
Full ADPIA audit defense support
Established mid-sized companies with complex multi-state risk
Rippling
Rippling Insurance / Broker flexible
$0 deposit standard
Top tier national carriers via API
Dynamic auto-split by remote work location
Full broker freedom
Real-time ledger audit reconciliation
Tech companies and distributed multi-state workforces
6. Stop-Work Orders, State Fines & Uninsured Injury Liability
Operating a business without active workers’ compensation insurance is treated by state regulatory agencies not merely as an administrative lapse, but as a severe criminal offense and civil fraud.
State Jurisdiction
Enforcement Action
Statutory Penalty Schedule
Personal Liability Exposure
California (Lab. Code § 3710.1)
Mandatory Stop-Work Order
$1,500 per employee in workforce; misdemeanor punishable by up to 1 year jail
10% penalty surcharge + full personal tort liability
New York (WCL § 52)
Stop-Work Order + Criminal Charges
$2,000 per 10-day period of non-compliance; felony for 5+ employees
Corporate officers personally liable for medical and wage claims
Florida (F.S. § 440.107)
Stop-Work Order
Penalty equal to 2x the premium the employer should have paid over prior 2 years
Immediate business operational freeze
Illinois (820 ILCS 305/4)
Civil Penalty & Work Prohibition
$500 per day of non-compliance ($10,000 minimum fine)
Class 4 felony for willful failure; personal asset attachment
The Loss of the Exclusive Remedy Shield
If an employer fails to maintain active workers’ compensation coverage and an employee suffers a catastrophic workplace injury, the employer loses the protection of the exclusive remedy doctrine. The injured worker is legally permitted to file a personal injury lawsuit against the company and its individual owners in civil court, seeking unlimited compensatory damages for pain and suffering, lost lifetime earnings, and punitive damages—liabilities that can instantly bankrupt a small business.
How does Pay-As-You-Go workers’ comp differ from traditional insurance?
Traditional workers’ compensation requires a 15% to 25% upfront down payment based on estimated annual payroll, followed by fixed monthly payments and a mandatory year-end audit invoice. Pay-As-You-Go requires $0 down payment, calculates exact premiums on actual payroll each pay run via software API, and eliminates year-end audit surprises.
Is Pay-As-You-Go workers’ compensation more expensive?
No. The underlying insurance premium rates are determined by state insurance commissioners and NCCI risk classifications, making the base rate identical. In fact, Pay-As-You-Go is significantly more cost-effective because it preserves operating capital by eliminating upfront cash deposits and billing finance charges.
Can I keep my existing insurance broker with Pay-As-You-Go payroll?
Yes, on platforms that support “Bring Your Own Broker” (such as Rippling and OnPay). Your existing broker remains the agent of record and earns their standard commission, while the payroll platform establishes an automated billing API feed to the insurance carrier. Other platforms (like Gusto or QuickBooks) may act as the broker of record directly.
What happens to workers’ comp if I hire an employee in another state?
You must add that state to your workers’ compensation policy under “Part 3 – Other States Insurance.” Workers’ compensation is governed by the state where the employee physically performs work. Platforms like Rippling and Gusto automatically detect remote state hiring and alert the insurance carrier to bind appropriate multi-state riders.
Are 1099 independent contractors covered under workers’ compensation?
Genuine 1099 independent contractors are responsible for securing their own insurance. However, during annual workers’ comp audits, insurance auditors will demand Certificates of Insurance (COI) proving each 1099 contractor carries their own policy. If an uninsured contractor is deemed misclassified or lacks a COI, the insurance auditor will assess their entire 1099 compensation into your payroll premium base.
{
“@context”: “https://schema.org”,
“@type”: “FAQPage”,
“mainEntity”: [
{
“@type”: “Question”,
“name”: “How does Pay-As-You-Go workers’ comp differ from traditional insurance?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Traditional workers’ comp requires a 15% to 25% upfront down payment based on estimated payroll, followed by fixed payments and a year-end audit invoice. Pay-As-You-Go requires $0 down payment, calculates exact premiums on actual payroll each pay run via software API, and eliminates audit surprises.”
}
},
{
“@type”: “Question”,
“name”: “Is Pay-As-You-Go workers’ compensation more expensive?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “No. The underlying insurance rates are set by state insurance regulators and NCCI classifications, making base rates identical. Pay-As-You-Go is more cost-effective because it eliminates upfront cash deposits and installment finance fees.”
}
},
{
“@type”: “Question”,
“name”: “Can I keep my existing insurance broker with Pay-As-You-Go payroll?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Yes, on platforms that support ‘Bring Your Own Broker’ (such as Rippling and OnPay). Your existing broker remains the agent of record, while the payroll platform establishes an automated billing feed to the carrier.”
}
},
{
“@type”: “Question”,
“name”: “What happens to workers’ comp if I hire an employee in another state?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “You must add that state to your policy under ‘Other States Insurance’ because workers’ comp is governed by where the employee physically works. Platforms like Rippling and Gusto detect remote hiring and prompt riders automatically.”
}
},
{
“@type”: “Question”,
“name”: “Are 1099 independent contractors covered under workers’ compensation?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Genuine 1099 contractors are responsible for their own coverage. However, auditors demand Certificates of Insurance (COI) for each contractor. If an uninsured contractor lacks a COI, the auditor will add their earnings to your premium base.”
}
}
]
}
Executive Benchmarks & Related Regulatory Guides
Explore cross-referenced statutory rules, vendor cost evaluations, and operational guides:
First impressions matter, but in employment operations, initial compliance matters even more. A disorganized onboarding process not only causes 20% of new hire turnover within the first 45 days—it routinely exposes businesses to severe federal penalties under immigration, tax, and labor statutes. In 2026, deploying modern employee onboarding software is critical to eliminate manual paperwork, automate Form I-9 and E-Verify checks, ensure timely state new hire reporting, and enroll workers instantly into payroll and benefits systems.
Executive Key Takeaways for Managing Partners, HR Leaders & People Operations:
Governing Statutory Authorities: Immigration Reform and Control Act (IRCA, 8 U.S.C. § 1324a / Form I-9 Employment Eligibility Verification), USCIS Alternative Procedure for Remote I-9 Document Examination (88 FR 47949), Internal Revenue Code § 3402(f) (Form W-4), Social Security Act § 453A (42 U.S.C. § 653a / Mandatory New Hire Reporting), and 29 CFR Part 516 (FLSA Recordkeeping).
Core Operational Lifecycle: Execute an airtight 5-stage onboarding sequence: (1) Digital pre-boarding packet distribution prior to Day 1, (2) Employee completion of Form I-9 Section 1 on or before the first day of work, (3) Employer physical or certified remote examination of identity and employment authorization documents within 3 business days, (4) Instant submission to USCIS E-Verify, and (5) Automated transmission to the State Directory of New Hires within 20 calendar days.
Existential Audit Liability: Immigration and Customs Enforcement (ICE) conducts unannounced workplace audits via Notices of Inspection (NOI). Form I-9 substantive paperwork violations trigger mandatory civil fines ranging from $281 to $2,789 per missing or deficient document under 8 CFR § 274a.10, while state new hire non-reporting triggers financial sanctions and child support compliance liens.
Platform Selection Framework: Gusto delivers seamless paperless onboarding integrated natively with payroll for small businesses; BambooHR provides rich cultural welcome flows and multi-department task checklists; Rippling provisions payroll, corporate benefits, IT hardware shipping, and cloud software accounts simultaneously in under 90 seconds; and Deel manages blended domestic and global contractor onboarding.
1. Quick Answer: Best Employee Onboarding Software for SMBs
The best employee onboarding software for small businesses in 2026 automates Form I-9 compliance, USCIS E-Verify remote verification, electronic W-4 collection, and direct payroll enrollment. Gusto delivers seamless paperless onboarding for general SMBs, BambooHR excels at structured cultural welcome flows, and Rippling provisions payroll, health benefits, and IT hardware simultaneously in under ninety seconds.
2. The Legal Architecture: Form I-9, USCIS Remote Verification & E-Verify
Every commercial employer operating within the United States must strictly verify the identity and employment authorization of every newly hired individual under 8 U.S.C. § 1324a. Federal immigration authorities enforce rigid statutory timelines and procedural rules:
Statutory Deadlines: Section 1 vs. Section 2
Section 1 (Employee Attestation): Must be completed by the employee no later than the first day of employment (Day 1). Employees attest under penalty of perjury to their citizenship or immigration status.
Section 2 (Employer Review and Verification): Must be completed by the employer within three (3) business days of the employee’s first day of work. The employer must physically examine (or remotely verify under authorized procedures) original unexpired documentation from List A (establishing both identity and employment authorization) or a combination of List B (identity) and List C (employment authorization).
Statutory Retention Rule: Employers must retain completed Forms I-9 for three (3) years after the date of hire or one (1) year after the date employment ends, whichever is later (8 CFR § 274a.2(b)(2)).
The DHS Alternative Procedure for Remote I-9 Examination
Under the Department of Homeland Security’s permanent framework (88 FR 47949), employers enrolled in E-Verify in good standing are authorized to examine I-9 documents remotely rather than requiring in-person physical inspection. To execute compliant remote verification, modern onboarding software must: (1) Ingest front and back high-resolution digital copies of candidate identity documents, (2) Facilitate a live video interaction between the employer and employee to inspect original documents in real time, and (3) Check the corresponding box in Section 2 indicating use of the Alternative Procedure. Utilizing non-compliant remote verification without E-Verify enrollment constitutes a substantive violation of federal law.
3. The 5-Stage Automated Onboarding Workflow from Pre-Boarding to Day 30
World-class onboarding systems orchestrate a structured, phased operational workflow that transforms compliance from an administrative roadblock into an automated background process:
Stage 1: Pre-Boarding Packet (3–7 Days Prior to Start)
Upon offer acceptance, the system automatically triggers a digital welcome flow. The candidate completes their IRS Form W-4, state tax withholding election, direct deposit authorization, and digitally signs employee handbook acknowledgments, emergency contacts, and proprietary information agreements before their official start date.
Stage 2: Day 1 Compliance & Provisioning
Section 1 of Form I-9 is verified as complete. The employee’s company laptop (pre-configured via MDM platforms like Rippling or Jamf) arrives with pre-installed security certificates and Single Sign-On (SSO) access to Google Workspace, Slack, and corporate portals. Automated welcome emails connect the new hire with their assigned mentor.
Stage 3: Day 3 Statutory Deadlines
Form I-9 Section 2 is executed and verified. The software automatically queries E-Verify and receives an instant Employment Authorized confirmation code, locking the immutable compliance timestamp into the company’s digital audit archive.
Stage 4: Day 20 New Hire Reporting
The software engine e-files the required new hire report to the State Directory of New Hires (42 U.S.C. § 653a), satisfying child support enforcement mandates without manual data entry.
Stage 5: Day 30 Benefits Open Enrollment Close
The new hire completes Section 125 health insurance, dental, vision, and 401(k) retirement elections. Deductions dynamically map directly to payroll tables without broker friction.
4. Mathematical Cost Model: Manual Paperwork vs. Automated Onboarding Software
To demonstrate the quantifiable economic value of automating onboarding workflows, the simulation below models an operational firm hiring 20 employees annually, comparing traditional manual paper-based onboarding against automated cloud software.
DIRECT ANNUAL LABOR & OVERHEAD SAVINGS: $9,560.00 (95.8% cost reduction)
Internal Hours Liberated: 150 hours of strategic HR and IT engineering capacity recovered.
5. Platform Comparison Matrix: Gusto, BambooHR, Rippling & Deel
The comparison matrix below evaluates the leading employee onboarding solutions across regulatory compliance automation, provisioning capabilities, and integration depth.
Platform
Pricing Structure
Form I-9 & E-Verify Integration
Pre-Boarding Mobile Experience
Direct Payroll / Benefits Auto-Enroll
IT Laptop & SaaS Provisioning
State New Hire Auto-Reporting
Best Fit Profile
Gusto
Included standard ($40 + $6 or $80 + $12)
Digital I-9 storage; integrated E-Verify
Gusto Wallet candidate portal
Native instant paystub sync
Basic app provisioning integrations
100% automated all 50 states
Small businesses seeking zero-addon payroll and onboarding unity
BambooHR
Advantage HRIS tier subscription
Digital e-signatures & audit trails
Award-winning customizable welcome packets
Syncs to BambooHR Payroll or external
Task checklists for IT teams
Supported via payroll connectors
Growing organizations prioritizing team culture and visual welcome workflows
Rippling
$8/user/mo platform core
Automated remote I-9 & E-Verify API
Modern mobile app digital flow
Native instant workforce database sync
Industry leader: Ships laptops, provisions 500+ apps in 90 seconds
100% automated all 50 states
Technology startups, distributed teams, and high-growth venture companies
Deel
Free US HR; $49/mo contractor; $599 EOR
Complete domestic & global compliance
Multi-language mobile onboarding
Native domestic & global contractor payouts
Global hardware equipment leasing
Automated domestic filing
Companies hiring blended domestic W-2 staff and international contractors
Federal scrutiny over employment eligibility verification has intensified. Immigration and Customs Enforcement (ICE) Homeland Security Investigations (HSI) issues thousands of Form I-9 Notices of Inspection (NOI) annually to commercial businesses across all industry sectors.
Enforcement Category
Statutory Code Violation
Civil Penalty Range per Violation
Software Compliance Guardrail
Substantive / Paperwork Violations
8 CFR § 274a.10(b)(2)
$281 to $2,789 per Form I-9 (missing dates, omitted signatures, expired documents)
Mandatory validation fields preventing form submission until all List items are valid
Knowingly Employing Unauthorized Workers
8 U.S.C. § 1324a(e)(4)
$5,579 to $22,324 per unauthorized worker; criminal penalties for pattern of practice
Up to $25 per employee ($500 for intentional conspiracy)
Automated digital state new hire reporting API triggered upon payroll enrollment
The 3-Day Notice of Inspection (NOI) Rule
When ICE serves a Notice of Inspection, employers have exactly three (3) business days to produce all Forms I-9 and supporting documentation. Searching through filing cabinets for paper forms completed years ago routinely leads to missing documents and massive fines. Cloud onboarding software enables administrators to generate a consolidated, audit-ready PDF export of all active and terminated Forms I-9—complete with immutable cryptographic audit timestamps—in less than five minutes.
Can an employer verify Form I-9 documents remotely over Zoom?
Only if the employer is formally enrolled and participating in USCIS E-Verify in good standing. Under the DHS Alternative Procedure (88 FR 47949), E-Verify enrolled employers may examine documents remotely via live video interaction after the employee uploads clear digital copies. Employers not enrolled in E-Verify must conduct in-person physical document examination.
What is the deadline for filing state new hire reports?
Under federal law (42 U.S.C. § 653a), employers must report newly hired or rehired employees to the State Directory of New Hires within 20 calendar days of hire (or semi-monthly if transmitting electronically). Modern onboarding software like Gusto and Rippling transmits this data automatically upon employee profile completion.
How long must an employer keep an employee’s Form I-9 after they leave?
Under 8 CFR § 274a.2, employers must retain completed Forms I-9 for three (3) years after the date of hire or one (1) year after the date of employment termination, whichever is later. Purging forms before this statutory window expires triggers civil paperwork penalties during an ICE audit.
What happens if an employee fails to complete Form I-9 Section 1 on Day 1?
Failing to complete Section 1 on or before the first day of work is a substantive violation of federal immigration law. During an ICE inspection, each late Form I-9 carries a statutory penalty ranging from $281 to $2,789. Onboarding software prevents this by requiring candidates to e-sign Section 1 during pre-boarding before their start date.
How does onboarding software integrate with IT hardware provisioning?
Advanced workforce management platforms like Rippling link HR onboarding directly to IT operations. When a new hire is added, the platform automatically orders, configures, and ships a pre-imaged company laptop to their home address, while simultaneously provisioning their business email, Slack, and cloud SaaS permissions based on their job title and department.
{
“@context”: “https://schema.org”,
“@type”: “FAQPage”,
“mainEntity”: [
{
“@type”: “Question”,
“name”: “Can an employer verify Form I-9 documents remotely over Zoom?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Only if the employer is formally enrolled and participating in USCIS E-Verify in good standing. Under the DHS Alternative Procedure, E-Verify enrolled employers may examine documents remotely via live video interaction after the employee uploads clear digital copies.”
}
},
{
“@type”: “Question”,
“name”: “What is the deadline for filing state new hire reports?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Under federal law (42 U.S.C. § 653a), employers must report newly hired or rehired employees to the State Directory of New Hires within 20 calendar days of hire. Modern software transmits this data automatically upon profile completion.”
}
},
{
“@type”: “Question”,
“name”: “How long must an employer keep an employee’s Form I-9 after they leave?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Under 8 CFR § 274a.2, employers must retain completed Forms I-9 for three (3) years after the date of hire or one (1) year after the date of employment termination, whichever is later.”
}
},
{
“@type”: “Question”,
“name”: “What happens if an employee fails to complete Form I-9 Section 1 on Day 1?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Failing to complete Section 1 on or before the first day of work is a substantive violation of federal immigration law. During an ICE inspection, each late Form I-9 carries a statutory penalty ranging from $281 to $2,789.”
}
},
{
“@type”: “Question”,
“name”: “How does onboarding software integrate with IT hardware provisioning?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Advanced platforms like Rippling link HR onboarding directly to IT operations. When a new hire is added, the platform automatically orders and ships a pre-configured laptop, while provisioning business email, Slack, and cloud software permissions.”
}
}
]
}
Executive Benchmarks & Related Regulatory Guides
Explore cross-referenced statutory rules, vendor cost evaluations, and operational guides:
Executive Key Takeaways: Small Business Health Insurance & Payroll Mechanics
Statutory Triad: Small employers (under 50 FTEs) face three compliant healthcare architectures: Traditional Small Group Major Medical (guaranteed issue via ACA), Qualified Small Employer HRAs (QSEHRA under IRC § 9831(d)), and Individual Coverage HRAs (ICHRA under 26 CFR § 54.9802-4). Standalone direct cash premium reimbursements are strictly illegal and trigger catastrophic excise taxes.
2026 Statutory Contribution Ceilings: QSEHRA mandates strict annual maximum reimbursement caps adjusted under IRS Rev. Proc. ($6,350 for self-only coverage; $12,800 for family coverage in 2026). Conversely, ICHRA has zero statutory contribution ceiling, empowering employers to define custom allowance tiers by formal employee class.
Section 125 FICA Tax Efficiency: Operating a Section 125 Premium Only Plan (POP) under IRC § 125 eliminates 7.65% in employer FICA/Medicare matching taxes on employee salary reductions and grants employees 100% pre-tax health premium deductions, yielding an immediate average savings of $459 per enrolled worker annually.
Mandatory W-2 Box 12 Reporting: QSEHRA non-taxable benefit allowances must be reported annually on Form W-2 in Box 12 using Code FF. Failure to report triggers information return penalties under IRC § 6721 up to $330 per uncorrected W-2 statement.
Excise Tax Shield: Direct cash subsidies for individual insurance outside an approved HRA or Section 125 vehicle violate ACA Market Reforms, exposing small businesses to devastating excise penalties under IRC § 4980D of $100 per day per affected employee ($36,500/year per worker).
Which health insurance option is best for small businesses?
Small businesses under 50 employees should choose QSEHRA for simple, capped tax-free reimbursements, ICHRA for uncapped class-based contributions across varied employee tiers, or traditional small group medical for unified employer-sponsored coverage. Administering benefits alongside automated payroll with a Section 125 plan guarantees full FICA tax deductibility while shielding owners from IRC § 4980D penalties.
Navigating healthcare options as a small employer requires mastering federal employee benefits law. The Patient Protection and Affordable Care Act (ACA) fundamentally altered employer healthcare responsibilities, yet many small business owners operating under 50 full-time equivalent employees (FTEs)—who are exempt from the ACA Employer Shared Responsibility Mandate under Internal Revenue Code (IRC) § 4980H—fall into catastrophic regulatory traps by reimbursing employees’ health insurance directly through standard wages or informal stipends.
The Illegality of Standalone Cash Reimbursements: IRC § 4980D
Under IRS Notice 2013-54 and Notice 2015-17, reimbursing an employee for their individually purchased health insurance policy without an ERISA-compliant group health plan violates the ACA’s annual dollar limit prohibition (PHS Act § 2711) and the preventive services requirement (PHS Act § 2713). Such arrangements are classified as non-compliant group health plans subject to IRC § 4980D excise penalties of $100 per day per affected employee—amounting to $36,500 annually per worker. Employers cannot simply add health stipends to gross payroll or write reimbursement checks without a formal statutory framework.
The QSEHRA Safe Harbor: IRC § 9831(d)
Enacted under the 21st Century Cures Act of 2016, IRC § 9831(d) created the Qualified Small Employer Health Reimbursement Arrangement (QSEHRA). To qualify:
Employer Size Threshold: The business must not be an Applicable Large Employer (ALE), meaning fewer than 50 full-time and full-time equivalent employees in the preceding calendar year.
No Conflicting Group Coverage: The employer cannot offer any group health plan (major medical, dental, vision, or FSA) to any of its employees simultaneously.
100% Employer Funded: Contributions must be funded entirely by the employer without employee salary deductions.
Same Terms Mandate: Benefits must be provided on the same terms to all eligible employees, though allowances may vary proportionally based on age and family size tiers.
2026 Statutory Reimbursement Caps: Annual reimbursements cannot exceed IRS index limits ($6,350 single / $12,800 family for 2026). Excess reimbursements lose tax-exempt status.
Mandatory Written Notice: Employers must provide an ERISA-compliant written notice to all eligible employees at least 90 days before the start of each plan year.
The Modern Flexibility Engine: ICHRA (26 CFR § 54.9802-4)
Promulgated via joint Treasury, Labor, and HHS final regulations effective January 2020, the Individual Coverage Health Reimbursement Arrangement (ICHRA) removed the restrictive employer-size limitations and financial contribution caps of QSEHRA. Governed by 26 CFR § 54.9802-4 and 29 CFR § 2590.702-2, an ICHRA allows businesses of any size to reimburse individual market major medical premiums and qualified medical expenses (IRC § 213(d)) on a 100% pre-tax basis.
Crucially, ICHRA enables class-based benefit segmentation. Employers can establish distinct allowance budgets across recognized statutory employee classes: Full-time employees, Part-time employees, Seasonal workers, Salaried vs. Hourly staff, Employees in distinct rating areas (states/regions), and Temporary workers. While employees within each defined class must receive equal allowances (subject only to age weighting), the employer maintains complete budgetary predictability without exposure to carrier underwriting rate spikes.
Section 125 Premium Only Plans (POP) & FICA Optimization
Under IRC § 125, employers sponsoring traditional group health plans or combining an ICHRA with individual health policies can establish a Cafeteria Plan / Premium Only Plan (POP). A POP permits employees to pay their portion of qualified health insurance premiums via pre-tax payroll deductions. This mechanism removes employee contributions from gross compensation subject to federal income tax withholding, Social Security tax (6.2%), and Medicare tax (1.45%). Employers simultaneously eliminate the 7.65% employer FICA matching liability on those deducted amounts, transforming healthcare administration into a direct self-funding operational savings engine.
Mathematical Worked Calculation Model: 10-Employee Cash-Flow & FICA Tax Audit
To evaluate the true cash-flow impact and statutory payroll tax liability across health benefit models, examine this comprehensive audit of a 10-employee professional services firm with an annual payroll of $650,000. All employees require single health coverage.
Executing a small business health insurance plan requires continuous synchronization between your benefits administrator and your payroll ledger to automate pre-tax Section 125 deductions, track HRA reimbursements, and produce accurate Form W-2 Box 12 reporting. Here is the operational comparison of top market architectures:
Platform
Primary Model Supported
Section 125 POP Integration
HRA Administration Capability
W-2 Box 12 Code FF Auto-Filing
Monthly Pricing (Base + Per User)
Best Operational Fit
Gusto
Traditional Group Medical & QSEHRA
Automated Native
Native QSEHRA / Partner ICHRA
Yes (Automated)
$40 + $6/mo (Plus tier $80+$12)
SMBs wanting all-in-one group insurance brokerage + payroll
Micro-businesses seeking standalone turnkey HRA compliance
Take Command
Enterprise ICHRA & Individual Exchange
Integrated Payroll Connect
Deep Class Modeling Engine
Exportable Box 12 Data
$20/mo + $15/enrolled worker
Growing companies building custom multi-state ICHRA budgets
QuickBooks Payroll
Traditional Group (SimplyInsured)
Automated Ledger Sync
Manual Reimbursement Setup
Manual Config Required
$45 + $6/mo (Core plan)
Firms strictly wanting standard group health tied to QBO accounting
ADP RUN
Group Medical & ADPIA Brokerage
Automated Native POP
Add-On Module
Yes (Automated)
Custom quote (~$79 + $4/mo)
Established SMBs desiring integrated insurance agency representation
Justworks PEO
Master Group Policy PEO Model
Full Co-Employment POP
N/A (Group Plans Only)
PEO W-2 Filing
$59 to $99/mo per employee
SMBs seeking Fortune 500-level group health rates via co-employment
Zenefits / TriNet
Group Medical & Open Broker Model
Integrated POP Engine
Third-Party Integration
Yes (Automated)
$10/mo/employee (HR base)
Companies bringing an independent broker into a modern HR portal
Regulatory Penalties, Form 720 PCORI Fees & Audit Defense
Operating an employer healthcare plan triggers overlapping audit scrutiny from the Internal Revenue Service, the Department of Labor (DOL), and state insurance commissions. Maintaining absolute audit readiness requires implementing strict administrative controls against the following statutory exposure points:
1. Section 125 POP Nondiscrimination Testing (IRC § 125(b))
To maintain the tax-exempt status of employee salary deductions, cafeteria plans must pass annual nondiscrimination tests:
The Eligibility Test: Measures whether non-highly compensated employees (NHCEs) are eligible to participate at rates comparable to highly compensated employees (HCEs).
The Benefits & Contributions Test: Ensures all participating employees receive equal access to pre-tax contribution benefits without discrimination in favor of HCEs.
The 25% Key Employee Concentration Test: Key employees (as defined in IRC § 416(i)(1)) cannot receive more than 25% of the total aggregate statutory nontaxable benefits provided to all employees under the plan. In closely held small businesses or family-owned enterprises, having owners and key executives take substantial pre-tax deductions can easily breach this 25% limit, causing the IRS to disqualify the plan retroactively and recharacterize deductions as taxable W-2 wages subject to back taxes and penalties.
2. Annual Form 720 PCORI Fee Obligations
Employers sponsoring self-insured health plans—which legally includes HRAs such as QSEHRA and ICHRA—are required by IRC § 4375 and § 4376 to pay the Patient-Centered Outcomes Research Institute (PCORI) fee. The fee is calculated on the average number of covered lives during the policy year and must be reported and paid annually using IRS Form 720 (Quarterly Federal Excise Tax Return) by July 31st. Failing to submit Form 720 triggers late filing penalties under IRC § 6651 of 5% per month up to 25% of the unpaid excise tax liability.
Employers providing a QSEHRA must report the total eligible benefit amount the employee was permitted to receive (not merely what was reimbursed) in Box 12 of Form W-2 using Code FF. If an employee claims an Advance Premium Tax Credit (APTC) on the health insurance marketplace while simultaneously receiving a QSEHRA benefit, the IRS cross-references Form W-2 Code FF against marketplace Form 1095-A data. Inaccurate Box 12 reporting will trigger automated IRS audit inquiries, notice CP2000 wage discrepancy audits, and potential employer reporting penalties under IRC § 6721 ($330 per incorrect return).
Advertisement: Related Payroll Compliance & Benefits Guides
Frequently Asked Questions (FAQ)
Can a small business owner simply reimburse employees directly for their individual health insurance?
No. Under IRS Notice 2013-54 and Notice 2015-17, reimbursing individual health insurance premiums outside of an ERISA-compliant group health plan, QSEHRA, or ICHRA is strictly prohibited under ACA Market Reforms. Doing so triggers severe excise tax penalties under IRC § 4980D of $100 per day per employee ($36,500/year per worker). All reimbursements must be structured through a formal statutory HRA.
What is the primary difference between a QSEHRA and an ICHRA?
A QSEHRA is restricted to small employers with fewer than 50 FTEs who do not offer any group health plans, and it imposes strict annual contribution caps ($6,350 single / $12,800 family in 2026). An ICHRA is available to employers of any size, has no statutory contribution limits, and permits employers to define different reimbursement amounts across distinct employee classes (e.g., salaried vs. hourly, full-time vs. part-time, geographic locations).
Can S-Corporation greater-than-2% shareholder-employees participate in a QSEHRA or ICHRA?
No. Under IRC § 1372, 2%-or-greater shareholders of an S-Corporation are treated as partners rather than common-law employees. Consequently, they cannot receive tax-free benefits through a QSEHRA, ICHRA, or Section 125 cafeteria plan. Instead, their health insurance premiums must be paid or reimbursed by the S-Corp, included in Box 1 of their Form W-2 as taxable compensation, and deducted as self-employed health insurance on Form 1040 Schedule 1.
How do pre-tax health insurance deductions save the employer money on payroll taxes?
When employee contributions toward health insurance premiums are processed through an IRC Section 125 Premium Only Plan (POP), those deduction amounts are excluded from gross wages subject to FICA taxes. This means the employer does not pay the 6.2% Social Security match or the 1.45% Medicare match on the deducted premiums—saving the employer $76.50 for every $1,000 paid by employees in pre-tax premiums.
What is the employer’s annual reporting duty for a QSEHRA on Form W-2?
Employers offering a QSEHRA must report the total amount of reimbursement the employee was eligible to receive during the calendar year in Box 12 of Form W-2 using Code FF. This amount is reported for informational purposes to coordinate marketplace Premium Tax Credit eligibility and is not treated as taxable income.
{
“@context”: “https://schema.org”,
“@type”: “FAQPage”,
“mainEntity”: [
{
“@type”: “Question”,
“name”: “Can a small business owner simply reimburse employees directly for their individual health insurance?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “No. Under IRS Notice 2013-54 and Notice 2015-17, reimbursing individual health insurance premiums outside of an ERISA-compliant group health plan, QSEHRA, or ICHRA is strictly prohibited under ACA Market Reforms. Doing so triggers severe excise tax penalties under IRC § 4980D of $100 per day per employee ($36,500/year per worker). All reimbursements must be structured through a formal statutory HRA.”
}
},
{
“@type”: “Question”,
“name”: “What is the primary difference between a QSEHRA and an ICHRA?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “A QSEHRA is restricted to small employers with fewer than 50 FTEs who do not offer any group health plans, and it imposes strict annual contribution caps ($6,350 single / $12,800 family in 2026). An ICHRA is available to employers of any size, has no statutory contribution limits, and permits employers to define different reimbursement amounts across distinct employee classes (e.g., salaried vs. hourly, full-time vs. part-time, geographic locations).”
}
},
{
“@type”: “Question”,
“name”: “Can S-Corporation greater-than-2% shareholder-employees participate in a QSEHRA or ICHRA?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “No. Under IRC § 1372, 2%-or-greater shareholders of an S-Corporation are treated as partners rather than common-law employees. Consequently, they cannot receive tax-free benefits through a QSEHRA, ICHRA, or Section 125 cafeteria plan. Instead, their health insurance premiums must be paid or reimbursed by the S-Corp, included in Box 1 of their Form W-2 as taxable compensation, and deducted as self-employed health insurance on Form 1040 Schedule 1.”
}
},
{
“@type”: “Question”,
“name”: “How do pre-tax health insurance deductions save the employer money on payroll taxes?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “When employee contributions toward health insurance premiums are processed through an IRC Section 125 Premium Only Plan (POP), those deduction amounts are excluded from gross wages subject to FICA taxes. This means the employer does not pay the 6.2% Social Security match or the 1.45% Medicare match on the deducted premiums—saving the employer $76.50 for every $1,000 paid by employees in pre-tax premiums.”
}
},
{
“@type”: “Question”,
“name”: “What is the employer’s annual reporting duty for a QSEHRA on Form W-2?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Employers offering a QSEHRA must report the total amount of reimbursement the employee was eligible to receive during the calendar year in Box 12 of Form W-2 using Code FF. This amount is reported for informational purposes to coordinate marketplace Premium Tax Credit eligibility and is not treated as taxable income.”
}
}
]
}
Executive Benchmarks & Related Regulatory Guides
Explore cross-referenced statutory rules, vendor cost evaluations, and operational guides:
For a 15-person company, deciding between a Professional Employer Organization (PEO) and standalone cloud payroll software is one of the most critical financial architecture decisions leadership will make. In 2026, the proliferation of API-driven HR platforms and certified co-employment models under Internal Revenue Code § 7705 has dramatically shifted the economics. While PEOs market enterprise-grade health insurance and outsourced compliance, the substantial per-employee administrative fee often creates a hidden financial drag that outstrips any health premium savings.
Executive Key Takeaways for CFOs & HR Directors:
Governing Federal Statutes: Internal Revenue Code 26 U.S.C. § 7705 (Certified Professional Employer Organizations), Treasury Regulation § 301.7705-1, and the Small Business Efficiency Act (SBEA).
Core Operational Mandate: Calculate true Total Cost of Ownership (TCO) by modeling per-employee administrative fees against health insurance pooling discounts, SUTA experience rating transfers, and workers’ comp policy terms.
Statutory Liability Transfer: Only an IRS-Certified PEO (CPEO) assumes sole statutory liability for federal employment taxes on Form 941 Schedule R; standard non-certified PEOs leave joint tax liability with the client company.
Break-Even Economic Threshold: For a professional services firm with 15 FTEs, modern standalone payroll software (such as Rippling or Gusto) saves an average of $14,000 to $22,000 annually over a PEO model unless specialized insurance pooling offsets the fee.
PEO vs. payroll software is the strategic choice between co-employment outsourcing under IRC § 7705—bundling payroll, compliance, and master health plans for $90–$160 PEPM—and running standalone cloud payroll software for $6–$14 PEPM. For a 15-person firm, software saves $14,000 to $22,000 annually unless specialized insurance discounts offset administrative fees. (See our cost model below).
Statutory Legal Framework: Co-Employment, IRC § 7705 & The SBEA
To accurately evaluate the two models, finance and HR leaders must understand the legal foundation of co-employment versus software-as-a-service (SaaS):
1. The Co-Employment Model (PEO Architecture)
Under a Professional Employer Organization contract, the hiring firm and the PEO enter into a statutory co-employment relationship. The PEO becomes the “employer of record” for federal and state tax reporting purposes, issuing paychecks under its own Federal Employer Identification Number (FEIN). The client company remains the “worksite employer,” retaining complete operational control over hiring, firing, day-to-day supervision, compensation levels, and product deliverables.
2. The Small Business Efficiency Act and IRS Certified PEOs (CPEO)
Congress established a formal federal regulatory framework for PEOs through the Small Business Efficiency Act (SBEA), codified under Internal Revenue Code Section 7705. Understanding whether a PEO is an IRS-Certified PEO (CPEO) is paramount:
Sole Statutory Tax Liability: Under IRC § 3511, if an IRS-Certified PEO fails to remit federal employment taxes (FICA, FUTA, and federal income tax withholding), the IRS can only seek recovery from the CPEO. The client company is statutorily released from liability. With a standard, non-certified PEO, the client company remains jointly liable if the PEO defaults.
Wage Base Restart Elimination: If a company joins or leaves an IRS-Certified PEO mid-calendar year, statutory wage bases for FICA ($168,600+ cap) and FUTA ($7,000 cap) carry over under IRC § 3121(a)(1) and § 3306(b)(1). With a non-certified PEO, joining mid-year forces the employer to restart the FUTA and FICA wage bases from zero, triggering duplicate payroll taxes.
3. The Standalone Payroll Software Architecture (SaaS Model)
When utilizing cloud payroll software (such as Rippling, Gusto, or ADP RUN), the client company remains the sole legal employer. Payroll taxes are calculated, drafted from corporate accounts, and remitted directly under the client firm’s unique FEIN and state tax account numbers. The employer maintains direct contracts for group benefits, retirement plans, and workers’ compensation policies.
The financial justification for a PEO typically hinges on two core mechanisms: group benefits purchasing power and state unemployment insurance (SUTA) experience ratings:
Health Insurance: Large-Group Master Policy vs. Small-Group Market
A 15-person company purchasing health insurance on the open market is evaluated under ACA small-group community rating rules. Small-group rates are based strictly on age and geographic location; an insurer cannot charge higher premiums based on employee health conditions or past claims history.
In contrast, a PEO aggregates thousands of worksite employees into a single large-group master policy. While large groups can theoretically negotiate lower administrative fees, they are subject to medical underwriting and claims experience. If the PEO’s broader risk pool experiences high medical claims, annual renewal rate hikes can exceed small-group trend lines.
State Unemployment Insurance (SUTA) Mechanics
Depending on state law, PEOs report unemployment taxes under either a client-level reporting or master-level reporting structure:
In master-reporting states, the client company adopts the PEO’s aggregate state experience rating. If the client has a high historical turnover rate, joining a PEO with a lower master rate can temporarily reduce SUTA tax payments.
However, if a client has a clean employment record with a rock-bottom SUTA rate (e.g., 1.2%), entering a PEO with an average master rate of 3.8% forces the business to pay thousands of dollars in unnecessary state unemployment taxes.
Mathematical Worked Model: 15-Person Company Total Cost Analysis
To quantify the financial reality, consider an institutional side-by-side cost model for a professional services technology firm with 15 full-time employees in 2026, generating $1,500,000 in total gross annual payroll ($100,000 average salary per employee):
Total Employment Administration Cost Formula:
Total Annual Overhead (TCO) =
  Administrative_Fees (Platform / PEO PEPM) +
  Employer_Health_Contribution (15 FTEs * Net Premium) +
  Workers_Comp_Premium (Gross Payroll * Net Rate) +
  Retirement_Plan_Administration (401k recordkeeping)
Small group: $565/mo per FTE × 15 × 12 = $101,700.00
PEO saves $4,500
Workers’ Comp Policy (Clerical 8810)
Master rate ($0.18 per $100 payroll) = $2,700.00
Standalone policy ($0.21 per $100 payroll) = $3,150.00
PEO saves $450
401(k) Plan Administrative Fee
Integrated PEO 401(k) plan = $0.00
Integrated provider (Guideline / Human Interest) = $1,140.00
PEO saves $1,140
Outside Compliance & HR Advisory
Included dedicated HR generalist support = $0.00
HR on-demand add-on ($50/mo) = $600.00
PEO saves $600
TOTAL ANNUAL EMPLOYMENT OVERHEAD
$121,500.00
$108,870.00
SOFTWARE SAVES $12,630 / YR
Conclusion of the Model: Even though the PEO generated $6,690 in insurance and 401(k) savings, its aggressive administrative fee ($21,600 vs. $2,280) wiped out the entire group purchasing advantage, costing the 15-person firm an extra $12,630 in annual cash outflow.
Software Architecture Matrix: PEO vs. Modern Cloud HRIS Platforms
Below is an objective capability and architectural breakdown across premier PEO providers and modern standalone cloud payroll engines:
Platform
Operating Model
Pricing (PEPM)
IRS CPEO Status
Benefits Broker Freedom
Ideal Company Profile
Justworks
Co-Employment (PEO)
$89–$99 / employee
Yes (IRS Certified)
Locked to Justworks Master Plans
Startups (5–30 FTE) wanting turn-key healthcare access without HR staff
TriNet
Co-Employment (PEO)
$125–$165 / employee
Yes (IRS Certified)
Industry-vertical master medical tiers
Biotech, hedge funds, and venture-backed tech demanding elite benefits
Rippling
Standalone SaaS (or Flex PEO)
$8 / employee + base
N/A (SaaS) / Yes (PEO option)
Complete: Bring your own broker (BYOB)
Fast-growing businesses wanting automated IT, HR, and custom insurance brokers
Gusto Plus
Standalone SaaS
$12 / employee + $80 base
N/A (SaaS Platform)
Embedded broker or bring your own (Plus)
Small businesses (1–50 FTE) prioritizing usability and simple compliance
While entering a PEO requires minimal paperwork, exiting a PEO presents substantial operational friction that CFOs must factor into long-term strategic plans:
1. Benefits Spin-Off and Open Enrollment Disruptions
Because employee medical coverage resides inside the PEO’s master contract, terminating a PEO agreement immediately terminates all employee health policies. The firm must coordinate a fresh small-group open enrollment, issue new insurance cards, establish separate HSA/FSA custodial accounts, and rebuild deductible accumulators so employees do not lose out-of-pocket progress.
When unwinding from a PEO, state unemployment agencies reassign the business to either its historical client experience rate or the statutory new employer rate (which can be as high as 3.5% to 5.0% depending on the state). Under the SUTA Dumping Prevention Act of 2004, transferring employees between entities to manipulate state unemployment tax rates carries civil penalties and criminal exposure.
Advertisement • Small Business Financial Consulting
Can a 15-person company get good health insurance without a PEO?
Yes. Under ACA small-group rules, companies with 1 to 50 employees have guaranteed access to small-group market plans from major carriers (Blue Cross, UnitedHealthcare, Aetna) through independent brokers or platforms like Gusto and Rippling, without requiring medical underwriting or PEO co-employment.
What is the difference between an IRS-Certified PEO (CPEO) and a standard PEO?
An IRS-Certified PEO (CPEO) meets rigorous bonding and independent auditing standards established under IRC § 7705. Crucially, client companies of a CPEO are legally protected from federal payroll tax liability if the CPEO fails to pay, and wage bases for FICA and FUTA carry over without resetting when joining or leaving mid-year.
Does a PEO protect my company from employee lawsuits?
Not completely. While PEOs often provide Employment Practices Liability Insurance (EPLI) and HR advisory services, the client company remains a co-employer and is named as a primary defendant in lawsuits involving wrongful termination, harassment, discrimination, or FLSA wage violations.
When does joining a PEO actually make financial sense?
A PEO makes financial sense if your company operates in high-risk manual labor industries where the PEO’s master workers’ compensation policy yields massive premium discounts, or if you have zero internal HR bandwidth and require complete outsourced benefits management across multiple remote states.
How long does it take to migrate from a PEO to standalone payroll software?
A standard migration from a PEO to standalone payroll software takes 4 to 8 weeks. It requires establishing state employer tax withholding and unemployment accounts, selecting standalone health insurance with a broker, setting up 401(k) recordkeeping, and transferring historical employee data.
{
“@context”: “https://schema.org”,
“@type”: “FAQPage”,
“mainEntity”: [
{
“@type”: “Question”,
“name”: “Can a 15-person company get good health insurance without a PEO?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Yes. Under ACA small-group rules, companies with 1 to 50 employees have guaranteed access to small-group market plans from major carriers through independent brokers or platforms like Gusto and Rippling, without requiring medical underwriting or PEO co-employment.”
}
},
{
“@type”: “Question”,
“name”: “What is the difference between an IRS-Certified PEO (CPEO) and a standard PEO?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “An IRS-Certified PEO (CPEO) meets rigorous bonding and independent auditing standards established under IRC § 7705. Crucially, client companies of a CPEO are legally protected from federal payroll tax liability if the CPEO fails to pay, and wage bases for FICA and FUTA carry over without resetting when joining or leaving mid-year.”
}
},
{
“@type”: “Question”,
“name”: “Does a PEO protect my company from employee lawsuits?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Not completely. While PEOs often provide Employment Practices Liability Insurance (EPLI) and HR advisory services, the client company remains a co-employer and is named as a primary defendant in lawsuits involving wrongful termination, harassment, discrimination, or FLSA wage violations.”
}
},
{
“@type”: “Question”,
“name”: “When does joining a PEO actually make financial sense?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “A PEO makes financial sense if your company operates in high-risk manual labor industries where the PEO’s master workers’ compensation policy yields massive premium discounts, or if you have zero internal HR bandwidth and require complete outsourced benefits management across multiple remote states.”
}
},
{
“@type”: “Question”,
“name”: “How long does it take to migrate from a PEO to standalone payroll software?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “A standard migration from a PEO to standalone payroll software takes 4 to 8 weeks. It requires establishing state employer tax withholding and unemployment accounts, selecting standalone health insurance with a broker, setting up 401(k) recordkeeping, and transferring historical employee data.”
}
}
]
}
Executive Benchmarks & Related Regulatory Guides
Explore cross-referenced statutory rules, vendor cost evaluations, and operational guides:
Executive BriefingSmall Business Retirement Architecture & Payroll Compliance (2026)
Executive Key Takeaways: Small Business 401(k) Providers & Payroll Integration
SECURE 2.0 Federal Startup Tax Credits: Under IRC § 45E (expanded by SECURE 2.0 Act § 102), employers with up to 50 employees receive a 100% startup administrative tax credit up to $5,000 annually for 3 years ($15,000 total) plus an employer matching contribution credit up to $1,000 per employee earning under $100,000, claiming via Form 8881.
Safe Harbor Exemption Architecture: Adopting an IRC § 401(k)(12) Safe Harbor design (basic match of 100% on first 3% plus 50% on next 2%, or 3% nonelective contribution) legally bypasses mandatory annual ADP/ACP nondiscrimination testing and Top-Heavy rules under IRC § 416, shielding business owners from refunding excess executive deferrals.
360-Degree Payroll Synchronization: Modern 401(k) providers (Guideline, Human Interest, Betterment) utilize automated two-way API integrations with payroll engines (Gusto, Rippling, QuickBooks) to process pre-tax deferrals, Roth post-tax withholdings, employer matching, and loan repayments, eliminating manual upload discrepancies.
The 7-Day DOL Deposit Safe Harbor: Under 29 CFR § 2510.3-102, employers with under 100 participants must deposit employee 401(k) withholdings into the plan trust within 7 business days following payday. Late deposits constitute prohibited transactions triggering a 15% excise tax under IRC § 4975 and mandatory Form 5330 reporting.
ERISA Fiduciary Liability Shield: Sponsoring employers serve as ERISA § 3(21) named fiduciaries by default. Contracting an integrated recordkeeper providing outsourced ERISA § 3(38) investment fiduciary and § 3(16) plan administrator coverage transfers legal liability for fund selection and Form 5500 filings away from the business owner.
Which 401(k) provider is best for small business payroll integration?
Guideline and Human Interest are the best small business 401(k) providers due to automated two-way payroll synchronization, built-in ERISA § 3(38) and § 3(16) fiduciary management, and low flat fee structures. Leveraging SECURE 2.0 startup tax credits offsets up to 100% of administrative fees while Safe Harbor plan designs bypass complex annual compliance testing.
Deploying an employer-sponsored retirement plan is governed by the Employee Retirement Income Security Act of 1974 (ERISA) and the Internal Revenue Code (IRC § 401). For decades, small businesses avoided offering 401(k) plans due to prohibitive administrative overhead, complex nondiscrimination testing, and fears of fiduciary litigation. However, the enactment of the Setting Every Community Up for Retirement Enhancement Act (SECURE Act of 2019) and SECURE 2.0 Act of 2022 fundamentally reshaped the economics of small business retirement programs.
SECURE 2.0 Startup Tax Credits: Form 8881 (IRC § 45E)
Under IRC § 45E, eligible small employers (1 to 50 employees who earned at least $5,000 in the preceding year) qualify for a 100% tax credit covering the ordinary and necessary costs of setting up and administering a new qualified retirement plan. The credit equals 100% of qualified startup costs up to an annual cap of $250 per non-highly compensated employee (NHCE), with a minimum of $500 and a statutory maximum of $5,000 per year for the first 3 tax years ($15,000 maximum administrative subsidy).
Additionally, SECURE 2.0 Section 102 created an additional employer contribution credit. Employers with up to 50 employees receive a federal tax credit equal to a percentage of employer contributions (matching or nonelective) made on behalf of employees earning under $100,000 (indexed), capped at $1,000 per employee. The credit is 100% in years 1 and 2, 75% in year 3, 50% in year 4, and 25% in year 5. For a 10-person firm, these provisions can eliminate virtually all administrative overhead and heavily subsidize employer matching costs.
Standard traditional 401(k) plans require onerous annual compliance tests to ensure that plan contributions do not unfairly favor owners and highly compensated employees (HCEs, defined in 2026 as individuals earning over $160,000 or owning >5% of the business):
Actual Deferral Percentage (ADP) Test: Compares pre-tax deferral rates of HCEs against NHCEs. If rank-and-file participation is low, HCE contributions are severely restricted or refunded with taxable penalties.
Actual Contribution Percentage (ACP) Test: Compares employer matching and employee after-tax contributions between HCEs and NHCEs.
Top-Heavy Test (IRC § 416): Triggers if key employees hold more than 60% of total plan assets as of the determination date, requiring minimum 3% employer contributions for all non-key staff.
Adopting an IRC § 401(k)(12) Safe Harbor Plan automatically exempts the employer from ADP, ACP, and Top-Heavy rules. Employers must commit to either: (1) a Basic Match (100% on the first 3% of deferred pay plus 50% on deferrals between 3% and 5%), (2) an Enhanced Match (e.g., 100% on the first 4%), or (3) a Nonelective Contribution (at least 3% of compensation to all eligible employees regardless of employee deferral). Safe Harbor contributions must be 100% immediately vested.
Automated 360-Degree Payroll Synchronization
Historically, administering a 401(k) required HR staff to manually download employee contribution deduction registers from payroll software and upload CSV files to a third-party recordkeeper following every pay cycle. A single clerical error could lead to late deposits, incorrect tax withholdings, or mismatched Roth classifications. Modern integrated recordkeepers maintain continuous two-way API webhooks:
Outbound Payroll Webhook: When an employee adjusts their contribution percentage or requests a loan repayment in the 401(k) portal, the deduction rate updates automatically in Gusto, Rippling, or QuickBooks without HR manual intervention.
Inbound Contribution Transmission: Upon payroll execution, employee gross compensation, pre-tax 401(k), Roth 401(k), and employer matching amounts are transmitted instantly to the custodian trust.
Census & Eligibility Tracking: Date of hire, hours worked, and termination dates flow automatically to the recordkeeper to calculate statutory eligibility and trigger automated auto-enrollment notices.
Examine this statutory financial model for a growing 10-employee software and services firm establishing a Safe Harbor 401(k) plan with 360 payroll integration. The model illustrates the net cash flow impact after applying SECURE 2.0 federal tax credits under Form 8881.
COMPANY CENSUS:
– 1 Business Owner (Key Employee / HCE): $160,000.00 Gross Compensation
– 9 Full-Time Employees (NHCEs): Average $60,000.00 Gross Comp each ($540,000.00 total)
– Total Covered Annual Payroll: $700,000.00
– Plan Design: Safe Harbor Basic Match (100% on first 3%, 50% on next 2% = 4% max match)
– Average Employee Deferral Rate: 5.0%
—————————————————————————————–
GROSS ANNUAL PLAN OPERATING EXPENDITURES:
1. Integrated Recordkeeper Administration (e.g., Guideline Core):
– Monthly Base Fee: $89.00 / mo × 12 = $1,068.00 / year
– Per-Participant Fee: $8.00 / participant / mo × 10 × 12 = $960.00 / year
– Annual Form 5500 Preparation & Filing Fee: $0.00 (Included in SaaS)
Total Annual Administrative & Software Fees: $2,028.00 / year
2. Safe Harbor Employer Matching Contributions:
– Owner Matching (4% of $160,000): $6,400.00 (Owner directly retains into retirement)
– 9 Employees Participating (assuming 7 enroll and defer >=5%):
7 NHCEs × $60,000 × 4% match = $16,800.00 / year
Total Employer Matching Outlay: $23,200.00 / year
GROSS ANNUAL PLAN CASH OUTLAY: $2,028.00 (Admin) + $23,200.00 (Match) = $25,228.00 / year
—————————————————————————————–
SECURE 2.0 FEDERAL TAX CREDIT ARBITRAGE (IRC § 45E / FORM 8881):
Credit 1: Plan Startup Administrative Tax Credit (§ 102(a)):
– 100% of Administrative Costs for employers with <= 50 employees (up to $5,000 max)
– Credit Applied: 100% of $2,028.00 = ($2,028.00) DOLLAR-FOR-DOLLAR TAX CREDIT
Credit 2: Employer Matching Contribution Credit (§ 102(b)):
– 100% of employer matching up to $1,000 per employee earning < $100k in Years 1 & 2
– 7 participating eligible NHCEs qualify for max $1,000 credit:
7 employees × $1,000.00 = ($7,000.00) DOLLAR-FOR-DOLLAR TAX CREDIT
TOTAL DOLLAR-FOR-DOLLAR FEDERAL TAX CREDITS: ($2,028.00 + $7,000.00) = ($9,028.00)
—————————————————————————————–
CORPORATE TAX DEDUCTION BENEFIT (COMBINED 21% FED + 6% STATE = 27% RATE):
– Net Remaining Deductible Employer Match:
Gross Match ($23,200.00) – Match Tax Credit Claimed ($7,000.00) = $16,200.00
– Corporate Tax Shield on Deductible Match: $16,200.00 × 27% = ($4,374.00)
—————————————————————————————–
NET ANNUAL EMPLOYER COST AUDIT:
Gross Total Cash Outlay: $25,228.00
Less Direct Federal Tax Credits (Form 8881): ($9,028.00)
Less Corporate Tax Deduction Savings: ($4,374.00)
NET AFTER-TAX COMPANY EXPENDITURE: $11,826.00 / year
LESS VALUE ACCRUED DIRECTLY TO BUSINESS OWNER:
Owner 401(k) Match Received Tax-Free: ($6,400.00)
Owner Max Personal 401(k) Deferral ($23,500 in 2026):
Owner Personal Income Tax Shield ($23,500 × 35% bracket): ($8,225.00)
—————————————————————————————–
NET OWNER/BUSINESS ECONOMIC SURPLUS: +$2,799.00 NET POSITIVE ARBITRAGE!
(The business saves more in taxes and owner wealth accrual than the net plan cost)
Small Business 401(k) Provider Architecture Comparison Matrix
Evaluating 401(k) recordkeepers requires assessing their fiduciary designations, payroll API integration capabilities, asset management pricing, and Form 5500 preparation automation. Here is how the top market providers compare:
Provider
Payroll Integration Type
Fiduciary Status
Safe Harbor Support
Form 5500 Prep & Signing
Pricing (Base + Per User + AUM)
Best Operational Fit
Guideline
Native 360° (Gusto, Rippling, QBO)
Full § 3(38) & § 3(16)
Automated Turnkey
Full Prep & E-Signing
$49 base + $8/mo (0.15% AUM)
SMBs using Gusto or QuickBooks wanting fully automated compliance
Human Interest
Universal 500+ Payroll Sync
Full § 3(38) & § 3(16)
Yes (Custom Vesting)
Full Prep & Filing
$120 base + $5/mo (0.00% AUM)
Companies using niche payroll engines needing zero AUM fee model
Companies with 20–100 employees desiring crypto/alternative asset windows
ADP Retirement Services
Native ADP RUN & Workforce Now
§ 3(21) Standard / 3(38) Opt
Yes
Automated 5500 Ready
Custom quote (~$150/mo + AUM)
Mid-sized enterprises already embedded deeply within ADP payroll ecosystem
Paychex Retirement
Native Paychex Flex Integration
§ 3(21) Advisor Partner
Yes
Included in Package
Bundled quote (~$120-$180/mo)
Established SMBs utilizing Paychex Flex HR seeking single-vendor billing
Gusto 401(k) (Guideline/Human Interest)
Deep Zero-Click Integration
Delegated § 3(38) / § 3(16)
Turnkey Guided Setup
Automated
Partner pricing ($39–$89/mo base)
Startups and small teams seeking single dashboard payroll-benefit sync
Slavic401k (PEO Model)
PEO Master Plan Integration
PEO Co-Fiduciary
Yes
Consolidated Master 5500
PEO Administrative Bundle
Companies operating inside a PEO (Justworks, Insperity) desiring PEP benefits
Fiduciary Compliance, Form 5500 Late Fees & DOL Audit Defense
The Department of Labor’s Employee Benefits Security Administration (EBSA) strictly enforces plan fiduciary conduct. The most common enforcement actions against small employers involve late contribution deposits and delinquent annual report filings:
Under DOL regulations, participant salary deferrals become plan assets on the earliest date they can reasonably be segregated from the employer’s general corporate assets. For small plans (under 100 participants), the DOL provides an absolute safe harbor: contributions deposited into the 401(k) trust within 7 business days following the payroll date are considered timely.
If an employer fails to meet this 7-day safe harbor and commingles funds with general working capital, the DOL classifies the transaction as an impermissible prohibited transaction under ERISA § 406(a)(1)(D). This triggers:
A mandatory 15% excise tax under IRC § 4975 on the lost earnings calculated using the IRS underpayment interest rate.
Mandatory filing of IRS Form 5330 (Return of Excise Taxes Related to Employee Benefit Plans) and payment of the tax.
Correction through the DOL’s Voluntary Fiduciary Correction Program (VFCP) to restore lost earnings to participant accounts. Failure to correct after notice elevates the excise tax to 100%.
2. Delinquent Form 5500 Filing Penalties
Qualified retirement plans must file Form 5500 or Form 5500-SF annually by the last day of the 7th month following the end of the plan year (July 31 for calendar year plans). Missing this deadline carries compounding statutory penalties:
Department of Labor Penalty: Up to $2,670 per day under ERISA § 502(c)(2) without statutory cap until filed.
IRS Late Filing Penalty:$250 per day under IRC § 6652(e), up to a maximum of $150,000 per late annual return.
Audit Mitigation: Employers with delinquent filings should immediately utilize the DOL’s Delinquent Filer Voluntary Compliance Program (DFVCP), which caps penalties at $750 for small plans ($4,000 max per plan for multi-year delinquencies) before an enforcement notice is issued.
For all new 401(k) plans established after December 29, 2022, SECURE 2.0 Section 101 mandates automatic enrollment (EACA) for all eligible employees at a default deferral rate between 3% and 10%, with an annual 1% automatic escalation up to at least 10% (max 15%). While businesses operating for less than 3 years or maintaining 10 or fewer employees are exempt from this mandate, any employer growing past 10 employees must ensure their payroll-401(k) integration automatically initiates default wage deductions to avoid plan operational failure penalties under the IRS Employee Plans Compliance Resolution System (EPCRS).
Advertisement: Related Retirement Compliance & Small Business Payroll Guides
Frequently Asked Questions (FAQ)
How do SECURE 2.0 tax credits reduce the cost of offering a 401(k)?
Under IRC § 45E, small businesses with up to 50 employees qualify for a 100% tax credit on plan setup and administrative fees, capped at $5,000 per year for the first 3 years ($15,000 total). Furthermore, employers receive a dollar-for-dollar tax credit up to $1,000 per employee earning under $100,000 for employer matching contributions in Years 1 and 2, claimed on IRS Form 8881.
What is a Safe Harbor 401(k) plan, and why do small businesses use it?
A Safe Harbor 401(k) plan requires the employer to make mandatory, immediately vested contributions to employees (such as a 4% basic match or 3% nonelective contribution). In exchange, the plan is legally exempt from annual IRS nondiscrimination testing (ADP/ACP tests) and Top-Heavy rules under IRC § 416, allowing business owners and executives to maximize their personal deferrals without risk of refunds.
What is the difference between an ERISA § 3(38) and § 3(16) fiduciary?
An ERISA § 3(38) investment manager assumes fiduciary responsibility for selecting, monitoring, and managing the plan’s investment options, protecting the employer from investment performance litigation. An ERISA § 3(16) plan administrator assumes operational fiduciary duty for plan management, including timely participant notices, compliance testing, and Form 5500 preparation and signing.
How quickly must employee 401(k) deductions be deposited into the trust?
Under 29 CFR § 2510.3-102, small employers (under 100 participants) must deposit employee salary deferrals into the plan trust within a 7-business-day safe harbor following payday. Failure to meet this timeline constitutes a prohibited transaction under ERISA § 406, triggering a 15% excise tax under IRC § 4975 and mandatory IRS Form 5330 reporting.
Can a business owner contribute to both a 401(k) and a Traditional or Roth IRA?
Yes. An eligible individual can contribute to both an employer-sponsored 401(k) plan (up to the $23,500 limit in 2026, or $31,000 if age 50+) and an IRA (up to $7,000 in 2026, or $8,000 if age 50+). However, active participation in a 401(k) plan subjects Traditional IRA contributions to income phaseout limits regarding tax deductibility under IRC § 219.
{
“@context”: “https://schema.org”,
“@type”: “FAQPage”,
“mainEntity”: [
{
“@type”: “Question”,
“name”: “How do SECURE 2.0 tax credits reduce the cost of offering a 401(k)?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Under IRC § 45E, small businesses with up to 50 employees qualify for a 100% tax credit on plan setup and administrative fees, capped at $5,000 per year for the first 3 years ($15,000 total). Furthermore, employers receive a dollar-for-dollar tax credit up to $1,000 per employee earning under $100,000 for employer matching contributions in Years 1 and 2, claimed on IRS Form 8881.”
}
},
{
“@type”: “Question”,
“name”: “What is a Safe Harbor 401(k) plan, and why do small businesses use it?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “A Safe Harbor 401(k) plan requires the employer to make mandatory, immediately vested contributions to employees (such as a 4% basic match or 3% nonelective contribution). In exchange, the plan is legally exempt from annual IRS nondiscrimination testing (ADP/ACP tests) and Top-Heavy rules under IRC § 416, allowing business owners and executives to maximize their personal deferrals without risk of refunds.”
}
},
{
“@type”: “Question”,
“name”: “What is the difference between an ERISA § 3(38) and § 3(16) fiduciary?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “An ERISA § 3(38) investment manager assumes fiduciary responsibility for selecting, monitoring, and managing the plan’s investment options, protecting the employer from investment performance litigation. An ERISA § 3(16) plan administrator assumes operational fiduciary duty for plan management, including timely participant notices, compliance testing, and Form 5500 preparation and signing.”
}
},
{
“@type”: “Question”,
“name”: “How quickly must employee 401(k) deductions be deposited into the trust?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Under 29 CFR § 2510.3-102, small employers (under 100 participants) must deposit employee salary deferrals into the plan trust within a 7-business-day safe harbor following payday. Failure to meet this timeline constitutes a prohibited transaction under ERISA § 406, triggering a 15% excise tax under IRC § 4975 and mandatory IRS Form 5330 reporting.”
}
},
{
“@type”: “Question”,
“name”: “Can a business owner contribute to both a 401(k) and a Traditional or Roth IRA?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Yes. An eligible individual can contribute to both an employer-sponsored 401(k) plan (up to the $23,500 limit in 2026, or $31,000 if age 50+) and an IRA (up to $7,000 in 2026, or $8,000 if age 50+). However, active participation in a 401(k) plan subjects Traditional IRA contributions to income phaseout limits regarding tax deductibility under IRC § 219.”
}
}
]
}
Executive Benchmarks & Related Regulatory Guides
Explore cross-referenced statutory rules, vendor cost evaluations, and operational guides: